
The Shops At Sunset Place In South Miami Sells For $65.5 Million To Alex Vadia's Midtown Equities
Midtown Equities, led by Alex Vadia, has acquired The Shops At Sunset Place for $65.5 million from FRIT Shops at Sunset Place, a joint venture between Federal Realty Investment Trust (NYSE: FRT), Grass River Property and The Comras Company.
Midtown Equities, led by Alex Vadia, has acquired The Shops At Sunset Place for $65.5 million from FRIT Shops at Sunset Place, a joint venture between Federal Realty Investment Trust (NYSE: FRT), Grass River Property and The Comras Company. The 9.7-acre, 524,180 square foot shopping center, which is located at 5701 SW 72nd St., Sunset Drive in South Miami, last traded for $111.5 million in 2015, representing a significant loss for the selling joint venture. The shopping center’s current occupancy is reportedly just below 60%, a significant gap from the reported 83% in March 2020.
The Shops at Sunset Place was initially developed in 1999 and plans have been approved for a major renovation which would include the addition of 414 rental apartments, 182 hotel rooms, reducing the retail component to 440,148 square feet and adding 32,840 square feet of office space. The impact of COVID-19 stalled the development plans when Federal Realty Investment Trust was hit with a $50.7 million net impairment charge in Q3 2020 when its $60.6 million non-recourse CMBS loan matured and was declared in default by the lender.
JP Morgan Chase Bank Office Building In Weston Sells For $8.9 Million
The JP Morgan Chase Bank office building in Weston, FL, has sold for $8.9 million. The 26,782-rentable-square-foot office building, anchored by JP Morgan Chase Bank, is located at 1040 Weston Road in the high-barrier-to-entry submarket that generates significant buyer interest. HRE/SEFIRA Weston Office, LLC, was the seller, and Shaked 21, LLC, was the buyer in the transaction which was overseen by Avison Young’s Florida Capital Markets Group.
The JP Morgan Chase Bank office building in Weston, FL, has sold for $8.9 million. The 26,782-rentable-square-foot office building, anchored by JP Morgan Chase Bank, is located at 1040 Weston Road in the high-barrier-to-entry submarket that generates significant buyer interest. HRE/SEFIRA Weston Office, LLC, was the seller, and Shaked 21, LLC, was the buyer in the transaction which was overseen by Avison Young’s Florida Capital Markets Group led by principals David Duckworth; John K. Crotty, CCIM; Michael T. Fay, who is also Managing Director of the firm’s Miami operations; Vice President Brian C. de la Fé; and Associates Emily Brais and Berkley Bloodworth.
“The Chase Bank building is 100% occupied and, with medical tenants comprising more than 60% of the tenancy, garnered notable investor interest in a market where buyers are seeking stable, recession-proof assets,” said Duckworth. “Ultimately, our team secured the right buyer for the sale, allowing our client to realize a positive return on investment during a pandemic after a three-year hold.”
Avison Young In 2017, the Avison Young team facilitated the sale of the same building to HRE/SEFIRA Weston Office, LLC, as part of a two-building portfolio spanning approximately 63,000 square feet for $13 million. The HRE/SEFIRA partnership, led by Highline Real Estate Capital Principal David Moret, completed a series of cosmetic improvements to the Chase Bank building which enabled ownership to increase occupancy from 84% to 100% and increase rental rates to generate a 52% gain in the price within three years.
“Overall, sales activity has picked up since the end of the third quarter and into the fourth, as buyers have more clarity on where the market is going and are eager to place capital,” said Crotty. “The buyer in this deal acquired a property that has performed extremely well throughout the pandemic and is poised to continue to do so as we transition into the new normal.”
One of the most desirable, high-barrier-to-entry suburban office locations in Broward County, Weston is part of the Southwest Broward submarket, the only submarket in the county to report positive net absorption in third-quarter 2020.
Ken Griffin Buys 10 Star Island For $25 Million, Bringing Star Island Assemblage To $95 Million
The multi-billionaire hedge fund magnate Ken Griffin, who founded the Chicago-based Citadel Securities, has expanded his Star Island assemblage with the acquisition of 10 Star Island for $25 million. In August 2020 an entity tied to Ken Griffin acquired the adjacent double lot with Miami Vice views of Downtown Miami at 11 and 12 Star Island Drive in an off-market deal for roughly $37 million.
The multi-billionaire hedge fund magnate Ken Griffin, who founded the Chicago-based Citadel Securities, has expanded his Star Island assemblage with the acquisition of 10 Star Island for $25 million. In August 2020 an entity tied to Ken Griffin acquired the adjacent double lot with Miami Vice views of Downtown Miami at 11 and 12 Star Island Drive in an off-market deal for roughly $37 million. Soon after, Griffin would purchase 13 Star Island for $32.5 million after the property was previously linked to Alex Rodriguez and Jennifer Lopez. The acquisition of 10 Star Island brings his assemblage to roughly $95 million.
Ken Griffin’s net-worth is estimated to be about $15 billion and he has been one of the largest luxury property buyers in the world over the past several years. In 2015 Griffin purchased two penthouses in Faena House on Miami Beach for a record at the time $60 million. He recently sold the larger of the two penthouses for $35 million and is now reportedly under contract to sell his second penthouse, which is currently listed for $12.5 million. In 2019 Griffin purchased a $240 million unit at 220 Central Park South in Manhattan, NYC, in a deal that broke the record for the most expensive residential transaction ever recorded in the U.S. In Palm Beach Griffin has assembled $350 million of land at Blossom Way and South Ocean Blvd. where he began buying in 2012.
The Estate Companies Acquires Site For Soleste NoMi Beach In North Miami Beach
The Estate Companies, a subsidiary of Estate Investments Group (EIG), has closed on the future site of Soleste NoMi Beach in North Miami Beach for $13.1 million. The project was approved in September 2020 and was designed by Form Group. The 1.78-acre site is located at 16395 Biscayne Blvd. and currently features an 8,249 square foot retail building which will be demolished.
The Estate Companies, a subsidiary of Estate Investments Group (EIG), has closed on the future site of Soleste NoMi Beach in North Miami Beach for $13.1 million. The project was approved in September 2020 and was designed by Form Group. The 1.78-acre site is located at 16395 Biscayne Blvd. and currently features an 8,249 square foot retail building which will be demolished. The seller was Biscayne Cove LLC, an entity managed by Enrique R. Puig, and the deal included $1 million in seller financing. When complete, Soleste NoMi Beach will rise 23-stories and will feature 367 apartment units, 2,708 square feet of commercial space and 655 parking spaces. Amenities will feature a pool deck, spa, fitness center, co-working space and a landscaped rooftop garden.
Urbanica Closes on Two New Lots In Edgewater For Hotel Development Project
Urbanica has recently acquired two new properties located in Edgewater as part of a land assembly that they started two years ago. The two purchased properties are next to each other and located at 237 NE 32 ST and 229 NE 32 ST, the closing price was $1.57M and $1.7M respectively.
Urbanica has recently acquired two new properties located in Edgewater as part of a land assembly that they started two years ago. The two purchased properties are next to each other and located at 237 NE 32 ST and 229 NE 32 ST, the closing price was $1.57M and $1.7M respectively. The transaction was overseen by Stefano Santoro of Current Real Estate. Urbanica now owns four lots for less than $10M in the same area, as they are planning to develop a full-service hotel featuring 12 stories and 200 rooms. The hotel will also include two floors dedicated to parking with 150 spaces, a Japanese Restaurant with 4,000 SF, 7,000 SF dedicated to event space with a banquette kitchen, and different amenities including a rooftop pool, gym, lobby and a game room on the ground floor.
The project is estimated to break ground in the second quarter of 2021, and the grand opening is planned to occur by the end of 2022. Urbanica started as a development company that grew its operations into real estate investment management, vertically integrating its company structure. Last summer, they also bought a site for $38M in Miami Beach. Urbanica currently owns multiple properties in Buenos Aires and the Miami area, including Urbanica The Meridian Hotel, Urbanica Euclid Hotel and Urbanica 5th, all of them located in Miami Beach.
By Eduardo Cohen
AMS Hospitality Led By Allen Morris Company And Stormont Hospitality Group Partners With Black Salmon To Launch $300 Million Joint Venture
AMS Hospitality, a joint venture between The Allen Morris Company and the Atlanta-based Stormont Hospitality Group, has teamed up with the Miami-based Black Salmon Capital to launch a $300 million initiative to acquire hospitality assets across the United States within the next 18 months.
AMS Hospitality, a joint venture between The Allen Morris Company and the Atlanta-based Stormont Hospitality Group, has teamed up with the Miami-based Black Salmon Capital to launch a $300 million initiative to acquire hospitality assets across the United States within the next 18 months.
In December the JV closed on its first acquisition, The Pelham Hotel, a 65-key boutique hotel in the heart of New Orleans. The Pelham Hotel is designated a historic landmark and ideally set adjacent to the vaunted French Quarter, within the city’s Central Business District. The property will undergo a complete, multi-million dollar renovation of the ground-floor lobby, public areas, and guest rooms in order to modernize its design and enhance the guest experience. New Orleans-based HRI Properties has been selected to provide property management services for the hotel
“The capability of this partnership to acquire and transform a hospitality asset is compelling,” said W. Allen Morris, Chairman & CEO of The Allen Morris Company. “This initial acquisition of The Pelham is an ideal of example of how we envision leveraging all facets of our varied strengths.”
The partnership between AMS Hospitality and Black Salmon leverages the key strengths and expertise of both firms across the disciplines of acquisitions, asset management, and capital raising. The JV will seek hotel properties that have undergone a price reduction from pre-pandemic values.
AMS Hospitality was formed earlier this year, joining The Allen Morris Company, one of the largest, diversified real estate firms in the southeast and Stormont Hospitality, a highly acclaimed hotel developer and asset manager.
Black Salmon Capital has acquired nearly $500 million of prime office buildings and senior housing assets across the United States, including US Bank Center in Phoenix, Arizona. It is a strategic partner of TSG Group, a developer of multifamily and offices. Black Salmon Capital’s investment strategy focuses on acquiring stabilized assets, in addition to value-add opportunities, in high growth markets with an educated workforce, a robust technology industry, and strong market fundamentals.
“We are delighted to mark Black Salmon’s foray into the hospitality industry with this deal,” said Jorge Escobar, CEO of Black Salmon. “Through our partnership with AMS, we will further our reach into the hospitality sector and generate new opportunities for our investors.”
“We are truly pleased to have partnered with a group of such consummate professionals across these various disciplines,” concludes Jim Stormont, co-founder of Stormont Hospitality Group, and President of AMS Hospitality. “We look forward to expanding our relationships and our portfolio within this sector while creating landmark assets.”
PMG Reveals MKDA-Designed Society Wynwood After Acquiring Final Piece of Assemblage For $11.5 Million
Property Markets Group (PMG) and Greybrook Realty Partners have submitted their plans for Society Wynwood for approval by the Wynwood Design Review Committee after acquiring the final piece needed for their 1.93 acre assemblage.
Property Markets Group (PMG) and Greybrook Realty Partners have submitted their plans for Society Wynwood for approval by the Wynwood Design Review Committee after acquiring the final piece needed for their 1.93 acre assemblage. The JV between PMG and Greybrook acquired 2407 NW 2nd Ave. for $11.5 million from a JV between RedSky Capital and JZ Capital Partners. The PMG and Greybrook JV acquired 1.6-acres at 2421-2455 NW 2nd Ave. in August 2019 for $46 million from the Doris D. Friedopfer Trust. Society Wynwood is part of PMG’s social community initiatives and when complete will span 522,008 square feet.
Society Wynwood will include 326 residential units, 41,258 square feet of retail space, 211 parking spaces and a 3,980 square feet underground lounge. The unit breakdown includes 96 studios spanning 410 square feet, 30 one-bedroom units spanning 654 square feet, 72 two-bedroom units spanning 780 square feet, 114 three-bedroom units spanning 1,190 square feet, and 6 four-bedroom units spanning 1,370 square feet. The building is designed by MKDA and features an interior courtyard, rooftop bar and restaurant, rooftop pool and spa deck with an outdoor theater, yoga area and BBQ area. The project will also feature murals on the side painted by Alexandre Farto, paying homage to Wynwood’s street art culture. Additionally, PMG will contribute to the Wynwood Public Benefit Trust Fund in exchange for a parking reduction of 192 parking spaces. The transit oriented project already benefited from a 30% parking reduction due to proximity to public transportation.
Scott Sherman’s Tricera Capital has a deal to acquire the commercial spaces upon completion of the project. PMG plans to break ground on Society Wynwood project in early 2021.
Royal Palm Companies Acquires 1.53-Acre Future Site of Legacy Hotel & Residences In Miami Worldcenter For $33.9 Million
Miami Worldcenter Associates, the master developer behind Miami Worldcenter, the $4 billion, 27-acre mixed-use development under construction in the heart of Downtown Miami, has sold a 1.53-acre parcel to Royal Palm Companies (RPC). The transaction includes 66,656 square feet of developable land that was sold for $33.9 million.
Miami Worldcenter Associates, the master developer behind Miami Worldcenter, the $4 billion, 27-acre mixed-use development under construction in the heart of Downtown Miami, has sold a 1.53-acre parcel to Royal Palm Companies (RPC). The transaction includes 66,656 square feet of developable land that was sold for $33.9 million. The property, which is situated at 942 Northeast First Avenue, will be home to the Legacy Hotel & Residences, a 50-story mixed-use tower with 274 branded residences atop a 256-room hotel. The Cushman & Wakefield team of Robert Given, Troy Ballard and James Quinn represented the seller, Miami Worldcenter Associates, in the transaction.
Legacy Hotel & Residences’ developer, Dan Kodsi of RPC, previously partnered with Miami Worldcenter Associates developers, led by Nitin Motwani and Art Falcone, on the newly completed Paramount Miami Worldcenter luxury condominium tower, which opened to residents in 2019 across the street.
“Legacy Hotel & Residences is one of our most anticipated developments. The project’s iconic architecture and state-of-the-art amenities featuring a world-class restaurant and medical facility are just some of the components that will make it a standout addition to our city-within-a-city at Miami Worldcenter,” said Nitin Motwani, Managing Partner of Miami Worldcenter Associates. “We’re committed to working with best-in-class developers to create a diverse and vibrant eco-system for the ultimate live, work, play Miami experience, and our recent collaboration with Dan Kodsi on Paramount is a testament to that vision.”
Legacy Hotel & Residences will feature first-of-its-kind amenities and offerings, including a sophisticated members-only international business lounge, a dramatic Singapore-inspired cantilevered pool, downtown’s largest hotel pool deck set on one acre, a highly-anticipated 100,000 square foot medical and wellness center, and stylish microLUXE residences – all topped with the project’s signature amenity: the city’s first enclosed rooftop atrium, taking up the top seven floors of the tower.
“We are looking forward to breaking ground in early 2021 on what we expect will be one of the iconic centerpieces of Miami Worldcenter,” said Dan Kodsi, CEO of RPC. “Legacy Hotel & Residences is setting the stage for the future of mixed-use developments and branded-residences that prioritize health and wellness without sacrificing luxury lifestyle experiences and resort-style amenities that discerning homeowners and travelers are accustomed to.”
The Miami Worldcenter master plan, delivering in phases, features an array of residential, commercial and hospitality uses. These include approximately 300,000 square feet of retail, restaurant and entertainment space; the 60-story Paramount Miami Worldcenter condominium tower; Caoba, a 444-unit apartment tower that opened in 2019; a 348-room CitizenM hotel which is now under construction; and Bezel, a 434-unit rental tower by ZOM Living which is also underway. In addition, Hines is preparing to build a new tower that will comprise up to 500,000 square feet of Class A office space and MDM Group is planning a 1,700-room Marriott Marquis hotel and adjacent 600,000 square foot expo center.
Miami Worldcenter occupies 10 city blocks within walking distance of Museum Park, home to Perez Art Museum Miami and the Frost Museum of Science; AmericanAirlines Arena; the Adrienne Arsht Performing Arts Center; and Miami-Dade College’s Downtown Miami campus. It is also adjacent to Virgin Trains’ MiamiCentral station, which will soon offer direct train service to Fort Lauderdale, West Palm Beach and Orlando, together with access to TriRail, the Metromover and the Metrorail, making Miami Worldcenter the largest and most-connected transit-oriented development in Florida.
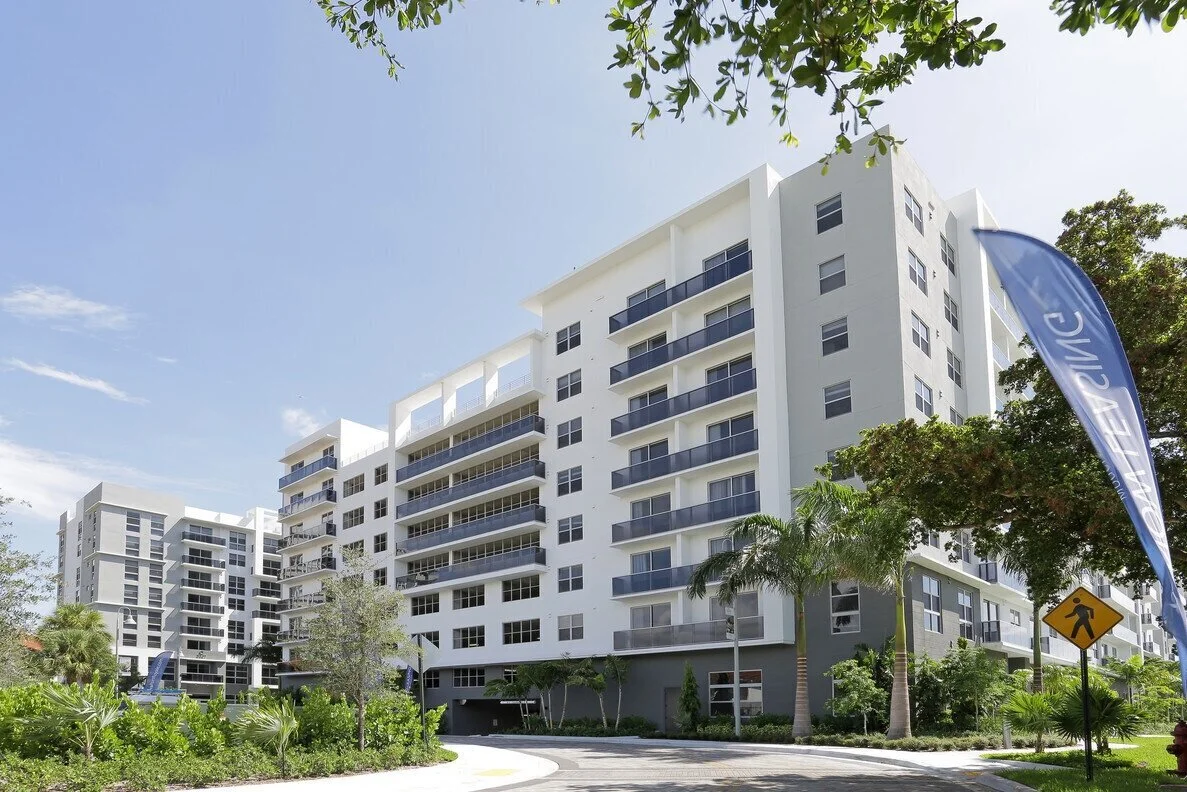
Northwestern Mutual Acquires Modera Port Royale In Fort Lauderdale For $180 Million
Northwestern Mutual has acquired the Modera Port Royale apartment community in Fort Lauderdale for $180 million. Modera Port Royale is located long the Intracoastal Waterway at 3303 Port Royale Drive South as well as 2890-2900 Port Royale Blvd.
Northwestern Mutual has acquired the Modera Port Royale apartment community in Fort Lauderdale for $180 million. Modera Port Royale is located long the Intracoastal Waterway at 3303 Port Royale Drive South as well as 2890-2900 Port Royale Blvd. The seller was Port Royale JV Phase I LLC, a joint venture between Mill Creek Residential and Invesco Real Estate and the buyer was NM-Port Royale LLC, an entity managed by Northwestern Mutual Life Insurance. The pricing breaks down to roughly $324,000 per unit.
Modera Port Royale features 555 rental apartment units spanning 1.03 million square feet spread across five buildings on an 8.2-acre site. Amenities include a waterfront pool, game room, coffee bar, fitness center, roof deck, theater and marina with 55 boat slips. The property was developed in 2017 by Mill Creek Residential who sold Phase 1 for $94 million in 2015.
Lennar Acquires Pine Isles Mobile Home Community In Homestead For $29 Million
Lennar Homes (NYSE: LEN) has acquired the former site of Pine Isles Mobile Home Community in Homestead for $29 million. The property is located at 28600 SW 132nd Ave. and spans 42.7 acres. Pines Isles Mobile Home Community serviced seniors and was disbanded in 2019 before the site was rezoned for the development of 456 single-family homes.
Lennar Homes (NYSE: LEN) has acquired the former site of Pine Isles Mobile Home Community in Homestead for $29 million. The property is located at 28600 SW 132nd Ave. and spans 42.7 acres. Pines Isles Mobile Home Community serviced seniors and was disbanded in 2019 before the site was rezoned for the development of 456 single-family homes. The seller was MAC Thirteen LLC, an entity tied to Rolando Delgado of Treo Group, who will receive a portion of the proceeds from each home sold. Delgado purchased the site in 2018 for $12.99 million.
Lennar Homes has already launched sales of the project, named Pine Vista, a master-planned community of townhomes and single-family homes with resort-style amenities. Homebuyers will have 14 different floorpans to choose from and single family homes will range from 1,833 square feet to 3,221 square feet and pricing from $357,990 to $419,990. Townhomes will start in the $200,000’s. Amenities will include a clubhouse, pool and park.


Bal Harbour Shops has unveiled its fully leased, 200,000-square-foot West Shops expansion, with 30 luxury boutiques and flagship stores and openings continuing through 2028.