
Aztec Group Arranges $12 Million In Financing For Publix-Anchored Kirkman Oaks Shopping Center
Aztec Group, Inc. has secured $12 million in non-recourse financing for Kirkman Oaks Shopping Center in Orlando, Florida, overseen by Brell Tarich and Charles Penan. Kirkman Oaks is an 98,000-square-foot neighborhood retail center anchored by Publix Supermarket and Davita Dialysis.
Aztec Group, Inc. has secured $12 million in non-recourse financing for Kirkman Oaks Shopping Center in Orlando, Florida, overseen by Brell Tarich and Charles Penan. Kirkman Oaks is an 98,000-square-foot neighborhood retail center anchored by Publix Supermarket and Davita Dialysis. The property is 98% occupied and ideally located just north of Universal Studios at 4606 S Kirkman Road, Orlando, FL.
“Grocery-anchored retail centers, especially those boasting Publix as their anchor, are highly coveted by lenders looking to put out capital in the current Covid-19 environment,” said Brell Tarich, Director of Aztec Group. “The borrower’s stellar track record coupled with the well-performing property allowed us to secure long-term financing at very attractive terms that exceeded the borrower’s expectations.”
The financing was provided by a Georgia Based regional bank. Financial terms of the non-recourse mortgage include a 7-year term, sub-3.5% fixed interest rate and a 30-year amortization schedule. The borrower is led by Daniel Halberstein, a seasoned retail and office investor based in Aventura, Florida.
“Kirkman Oaks benefits from its exceptional infill location at the main intersection of one of Orlando’s premier submarkets,” added Charles Penan, Executive Vice President of Aztec Group. “The terms of this financing speak to the strength of both the ownership and the asset itself.”
Carlos Mattos And Family Acquire Waterway Shoppes of Weston For $20.45 Million
An entity tied to the Mattos family, led by Carlos Mattos and his children, Nicolas and Isabella Mattos, have acquired the Waterway Shoppes of Weston for $20.45 million, roughly $501 per square foot. Waterway Shoppes of Weston was developed in 1999 and was acquired by the seller, Waterway Ventures LLC, an entity tied to Fondo Atlas and Dylan Fonseca, for $15.3 million in May 2015.
An entity tied to the Mattos family, led by Carlos Mattos and his children, Nicolas and Isabella Mattos, have acquired the Waterway Shoppes of Weston for $20.45 million, roughly $501 per square foot. Waterway Shoppes of Weston was developed in 1999 and was acquired by the seller, Waterway Ventures LLC, an entity tied to Fondo Atlas and Dylan Fonseca, for $15.3 million in May 2015. The property was listed with Kirk Olson and Drew Kristol of Marcus & Millichap for $20.65 million. Gordon Messinger of Cushman & Wakefield represented the buyer in the transaction. The acquisition was financed with a $9.98 million CMBS loan provided by Deutsche Bank.
Waterway Shoppes of Weston is located at 2210-2282 Weston Rd. and spans 40,848 square feet on 4.95 acres of land. Tenants include AT&T, Hooters, Lucille’s American Café, Chill-N Nitrogen Ice Cream, Cyclebar, BankUnited, Lucille’s American Café, Baires Grill and Pearl Vision Center.
MG Developer Locks Down $16.5 Million In Equity Financing To Complete Coral Gables Luxury Townhome Projects
MG Developer, led by CEO Alirio Torrealba, has locked down $16.15 million in equity financing to complete two luxury townhome projects in Coral Gables, Biltmore Row and Althea Row. The projects are currently under construction after broking ground in February 2020.
MG Developer, led by CEO Alirio Torrealba, has locked down $16.15 million in equity financing to complete two luxury townhome projects in Coral Gables, Biltmore Row and Althea Row. The projects are currently under construction after broking ground in February 2020. The financing was provided by PBVMF 23 LLC and was arranged by Jeffrey Donnelly and Dmitry Levkov of Colliers International South Florida.
The projects are being developed as part of MG Developer’s Biltmore Square, which features MG Developer nearby projects including apartment projects Biltmore Parc and the recently sold-out Beatrice Row. Biltmore Row features 10 townhome units and is located at 760 Valencia Ave. while Althea Row features 5 townhome units and is located at 735 Almeria Ave. Each townhome under development offers 4 bedroom floor plans and range from 4,514 to 5,524 square feet, featuring terraces, private loggias and luxurious finishes. Pricing starts just over $3 million per unit.
Bell Partners Acquires Boca Raton Multifamily Communities For $94.25 Million
The Greensboro, NC-based Bell Partners has acquired two apartment communities in Boca Raton, The Lumin at Boca Raton and Cade Boca Raton, for $94.25 million. The Lumin at Boca Raton and Cade Boca Raton are located within the Park at Broken Sound, at 5500 Broken Sound Blvd. and 950 NW Broken South Parkway respectively.
The Greensboro, NC-based Bell Partners has acquired two apartment communities in Boca Raton, The Lumin at Boca Raton and Cade Boca Raton, for $94.25 million. The Lumin at Boca Raton and Cade Boca Raton are located within the Park at Broken Sound, at 5500 Broken Sound Blvd. and 950 NW Broken South Parkway respectively. The acquisition was financed by a $58.8 million mortgage provided by GIM Commercial Mortgage Loan Fund. The properties will be renamed Bell at Broken Sound. Bell Partners now owns eight apartment communities in South Florida.
5500 Broken Sound Blvd. is a 180-unit apartment complex completed in 2018 on 9.1 acres. The property was developed and sold by a joint venture between Mainstreet Capital Partners and New Century Companies and sold for $56.5 million, roughly $314,000 per unit. 950 NW Broken Sound Parkway was also completed in 2018 and features 90 townhomes on 5-acres. The property was sold by an affiliate of Bluerock Real Estate and sold for $37.75 million, roughly $419,000 per unit.
Fontainebleau Miami Beach Exits Special Servicing On $975 Million CMBS Loan
Jeffrey Soffer’s Fontainebleau Miami Beach has exited special servicing on its $975 million commercial mortgage-backed security loan (CMBS). When issued in November 2019, the loan was the largest CMBS hotel loan in South Florida. The loan entered special servicing on March 30 amid the onset of the COVID-19 pandemic and following a modification request.
Jeffrey Soffer’s Fontainebleau Miami Beach has exited special servicing on its $975 million commercial mortgage-backed security loan (CMBS). When issued in November 2019, the loan was the largest CMBS hotel loan in South Florida. The loan entered special servicing on March 30 amid the onset of the COVID-19 pandemic and following a modification request. The loan was returned to its master servicer on September 23 and payments reportedly remained current throughout the special servicing period, although as part of a forbearance agreement monthly reserve payments have been deferred to 2021; additionally, the hotel’s 2020 financials will not be used when calculating the property’s debt yield.
CMBS loans, which are secured by a mortgage on a commercial real estate property, are among the hardest to restructure as under the typical CMBS structure. A loan is transferred into a CMBS pool and a Master Servicer administers the loan. The Master Servicer is generally not permitted to enter into a loan modification or restructuring agreement and a Special Servicer is needed to potentially modify or restructure an individual loan in a CMBS pool. When loans are in special servicing the borrower cannot take out new debt or refinance their property.
South Florida’s hotels have bit hit with some of the hardest economic impact from COVID-19 where the industry must meet nearly $4.2 billion in CMBS payments. Miami Beach hotels, motels and short-term rentals were ordered shut on March 23 and have laid off thousands of employees. Fontainebleau Development also owns the JW Marriott Turnberry Miami, Turnberry Isle Marina, Turnberry Ocean Club and The Big Easy Casino in Hallandale Beach.
The Fontainebleau Miami Beach opened in 1954 and was designed by architect Morris Lapidus. The property spans more than 15 acres with 11 pools, a 40,000 SF spa, and 12 different restaurants and bars including Hakkasan and LIV Nightclub. The hotel is made up of four towers including the Chateau and Versailles towers with 846 hotel rooms as well as the Tresor and Sorrento towers with 748 condo-hotel units. It was acquired by Turnberry Associates for $325 million in 2005.
Elevate Partners Locks Down $92 Million In Financing For The Newly Completed Four West Las Olas Apartment Tower
Elevate Partners, led by Scott Bodenweber and Tom Vogel, have locked down $92 million in 3-year bridge financing with optional extension for Four West Las Olas. The loan was provided by the New York-based Benefit Street Partners Realty Trust, who provided $76 million of senior debt, and the West Palm Beach-based Electra Capital who provided $16 million in mezzanine financing.
Elevate Partners, led by Scott Bodenweber and Tom Vogel, have locked down $92 million in 3-year bridge financing with optional extension for Four West Las Olas. The loan was provided by the New York-based Benefit Street Partners Realty Trust, who provided $76 million of senior debt, and the West Palm Beach-based Electra Capital who provided $16 million in mezzanine financing. Four West Las Olas was roughly 60% leased at the time of refinancing. The loan was brokered by Denny St. Romain of Cushman & Wakefield with Dan McCawley of Greenberg Traurig representing the developer. The new loan replaces an $80 million construction loan provided by Trez Forman Capital in 2018.
Four West Las Olas was completed in Q1 2020 and rises 25-stories. The tower offers 260-units which range from 588 square feet studio layouts to 1,376 square feet 3 bedroom residences. Pricing ranges from $1,724 /mo. to over $7,000 /mo. Four West Las Olas also features 12,000 square feet of retail and 407 parking spaces. Amenities include a rooftop pool, sky club room, fitness center, speakeasy style piano lounge, demonstration kitchen, residents’ lounge, coffee bar and business center.
Coral Rock Development Group Closes On $53.5 Million In Construction Financing For Pura Vida Hialeah
Miami-based Coral Rock Development Group has announced that they have closed on a $53.5 million participating construction, mini perm loan for the residential portion of Pura Vida Hialeah, a nine-acre mixed-use project that is transforming Hialeah and is set to be the first of its kind in the area in more than 20 years. Principal Real Estate Investors served as the lender.
Miami-based Coral Rock Development Group has announced that they have closed on a $53.5 million participating construction, mini perm loan for the residential portion of Pura Vida Hialeah, a nine-acre mixed-use project that is transforming Hialeah and is set to be the first of its kind in the area in more than 20 years. Principal Real Estate Investors served as the lender.
“We are very proud to secure construction financing with Principal Real Estate Investors for Pura Vida Hialeah as we step closer to delivering this compelling project to the area,” said Michael Wohl, principal of Coral Rock Development Group. “Pura Vida will undeniably introduce a new lifestyle for Hialeah creating a contemporary and convenient new walkable hub for residents and the surrounding neighborhood, and this is a momentous milestone in bringing this vision to fruition.”
Pura Vida Hialeah portends to transform the area’s aging residential and retail offerings with the first new sleek contemporary designed vertical towers. Boasting a vibrant mix of popular restaurants, shops and other conveniences, Pura Vida Hialeah will provide an exceptional pedestrian-friendly lifestyle, adding a much-needed benefit to the densely populated community.
The visionary project will encompass three eight-story residential towers consisting of 260 apartment units, with one tower offering approximately 11,000 square feet of ground floor retail; as well as three separate outparcels consisting of approximately 40,000 square feet of commercial retail space.
“Principal has worked with the Coral Rock Development team for almost two years to help make this project a reality. We believe not only in the Hialeah market, but especially in the team’s vision and experience. Pura Vida will truly be a game changing development in this community,” said Mary Scott, Senior Investment Director at Principal Real Estate Investors.
The project is poised to become the new epicenter of Hialeah. Offering a wide array of floorplans ranging in size from 538 square feet to 1,099 square feet, the market-rate rental residences at Pura Vida Hialeah will include studios, one, two, and three-bedroom units. Featured amenities will include a resort-style pool, state-of-the-art gym, BBQ area, dog park, biking center, and 24-hour security staff for the convenience of residents.
General contractor KAST Construction will break ground on the residential portion of the project next month and will open for occupancy in the first quarter of 2022.
The retail portion of the project broke ground in April 2019, recently completing the first building this summer with retail tenant Dollar Tree now open, and soon to be joined by InnovaCare Health. InnovaCare Health will occupy 20,000 square feet providing Pura Vida residents and the surrounding neighborhood with accessible healthcare services.
Additional confirmed retail tenants include a Wawa convenience store and gas station – representing one of the first outposts in Miami-Dade County for the rapidly expanding chain, and a Taco Bell restaurant, with more to be announced in the coming months.
Situated on a prime corner at 3051 W 16th Avenue, Pura Vida Hialeah boasts a central location just minutes from major thoroughfares including I-75, the Palmetto Expressway, the Florida Turnpike and Okeechobee Road, offering direct access to Greater Miami and the surrounding areas.
Cardone Capital Acquires Port Royale Apartments In Fort Lauderdale Via Crowdfunding Campaign
Cardone Capital, led by the “10X Rule” author and founder of the 10X Movement Grant Cardone, has acquired the Port Royale Apartments in Fort Lauderdale in one of the largest crowdfunding real estate deals to ever close in South Florida.
Cardone Capital, led by the “10X Rule” author and founder of the 10X Movement Grant Cardone, has acquired the Port Royale Apartments in Fort Lauderdale in one of the largest crowdfunding real estate deals to ever close in South Florida. Port Royale Apartments features 533 units located on the Intracoastal Waterway at 3101 Port Royale Blvd. and 3201-3300 Port Royale Drive in Fort Lauderdale. The property spans over 36 acres with a private marina. The property also has development rights to build an additional 292 units.
The deal closed for roughly $130 million, although the closing price has not yet been made public. The acquisition was financed with a $79.24 million, 10-year interest only loan at 2.3% from CBRE Multifamily Capital. The transaction was completed by the transfer of the Delaware-registered Port Royale Propco LLC. from Waterton Residential LLC to Cardone Capital, avoiding the need to pay documentary stamp taxes. Cardone Capital led a successful crowdfunding campaign for the equity piece, reportedly raising a $50 million. The Chicago-based Waterton Residential was the seller who was represented by Robert Given of Cushman & Wakefield. Waterton Residential initially acquired the apartment complex for $94 million in 2015.
Port Royale Apartments was originally developed in 1991 and renovated in 2016. Units range from one-bedroom, one-bathroom 540 SF units asking $1,400 per month up to two-bedroom, two-bathroom 1,000 SF units asking $2,247. Units include wood plank-style floors, full equipped kitchens, ceramic tile flooring in kitchens and baths, Juliette balconies, in-unit washer/dryers and walk-in closets. Amenities include a car wash area, residents lounge, outdoor barbecue and dining area, gated entrance, storage units and walking paths.
Cardone Capital now has 8,275 residential units and 26 properties in its portfolio. The Aventura-based real estate investment firm as raised over $440 million through crowdfunding to-date. Cardone Capital plans to be aggressive in multifamily acquisitions over the next several months, expecting to close on another $350 million in transactions.
Bar Invest Group Acquires Visions at Willow Pond Multifamily Community In West Palm Beach For $56.23 Million
The Miami-based private equity group Bar Invest Group, led by Jacques and Herve Barbera, have acquired the Visions at Willow Pond apartment community in West Palm Beach for $56.23 million. Visions at Willow Pond, which is located at 4860 Sandstone Lane, was built in 1987 and was fully renovated in 2013.
The Miami-based private equity group Bar Invest Group, led by Jacques and Herve Barbera, have acquired the Visions at Willow Pond apartment community in West Palm Beach for $56.23 million. Visions at Willow Pond, which is located at 4860 Sandstone Lane, was built in 1987 and was fully renovated in 2013. The 300 unit community spans 14.3 acres and 347,790 square feet of total development, breaking down the acquisition cost to roughly $187,433 per unit. The acquisition was financed with a $36 million loan provided by BankUnited NA.
Visions at Willow Pond features a fitness center, tenant lounge, tennis courts and a community swimming pool. The property was reportedly 95% occupied at the time of acquisition and traded at a 4.8% cap rate. The seller was the New York City-based Axonic Capital who was represented by Tal Frydman, Avery Klann, Hampton Beebe, Tyler Minix and Jonathan Senn of ARA Newmark.
Over the past year Bar Invest Group has become a major player in the South Florida multifamily sector having also acquired the 405 unit Sunny Lake apartment community in Fort Lauderdale. Since the formation of Bar Invest Group USA in 2001, the firm has partnered with Constructa Group for the development and delivery of Mary Brickell Village in addition to having developed or acquired over 1,500 apartments homes and 600,000 square feet of retail with a total investment in excess of $400 million.
The Estate Companies Secures $36M Construction Loan For Luxury Rentals in Miami's Health District
The Estate Companies, a leading developer of luxury multi-family developments throughout South Florida, has secured a $36 million construction loan from Bank OZK for Soleste Spring Gardens, an eight-story Class A, 240-unit luxury rental community at 1033 Spring Garden Rd. within the Miami’s historically designated Spring Garden district and Health District. The closing took place September 9th.
Soleste Spring Gardens will offer studios, one- and two-bedroom units ranging in size from 400 to 1,100 square feet. Like all projects within the Soleste Living brand portfolio, Soleste Spring Gardens will be a highly amenitized development with a vast collection of health and wellness offerings, social components and pet-friendly features, including a resort-style pool with spacious sun deck and private cabanas, outdoor kitchen and bar, dog park, pet spa, yoga lawn and electric car charging stations.
“Soleste Spring Gardens represents a major investment in the historic Spring Gardens District, an area we have been extremely bullish on for quite some time,” stated Jeffrey Ardizon, principal, The Estate Companies. “We have a strong track record of strengthening neighborhoods by offering luxury rentals at an attainable price point. I take my hat off to Bank OZK, along with all of our partners, for their continued commitment and confidence in our business plan. The entire team worked tirelessly to get this project financed in record time.”
Ardizon added, “The Miami Health District is home to the nation’s premier medical and research programs and a growing hub for the biotech industry. We look forward to delivering a Class A community to this quaint yet burgeoning area.”
Soleste Spring Gardens offers a bevy of conveniences for working professionals who will value its central location and access to public transportation. The site is just two blocks from the Culmer Metrorail Station, which provides a six-minute ride to the Brightline rail stop, and abuts on one of Miami’s main arteries, the Dolphin Expressway. Soleste Spring Gardens is also less than three miles from Brickell and the Downtown Miami office market, which represents the largest office market in South Florida, and is in close proximity to Downtown Miami’s Arts & Entertainment District, Midtown Miami, the Miami Design District and Wynwood.
Miami’s Health District is the second-largest medical district in the U.S. after Houston with approximately 30,000 employees and home to world-famous Jackson Memorial Hospital and the University of Miami Hospital.
The Estate Companies is also developing Miami’s second large-scale opportunity zone development, Soleste Grand Central in Downtown Miami, and recently acquired of a five-acre site occupied by a former Ramada Hotel in Hialeah with plans for redevelopment. In addition to Soleste Spring Gardens, the firm plans to break ground on two new projects this year in Dania Beach and North Miami Beach.
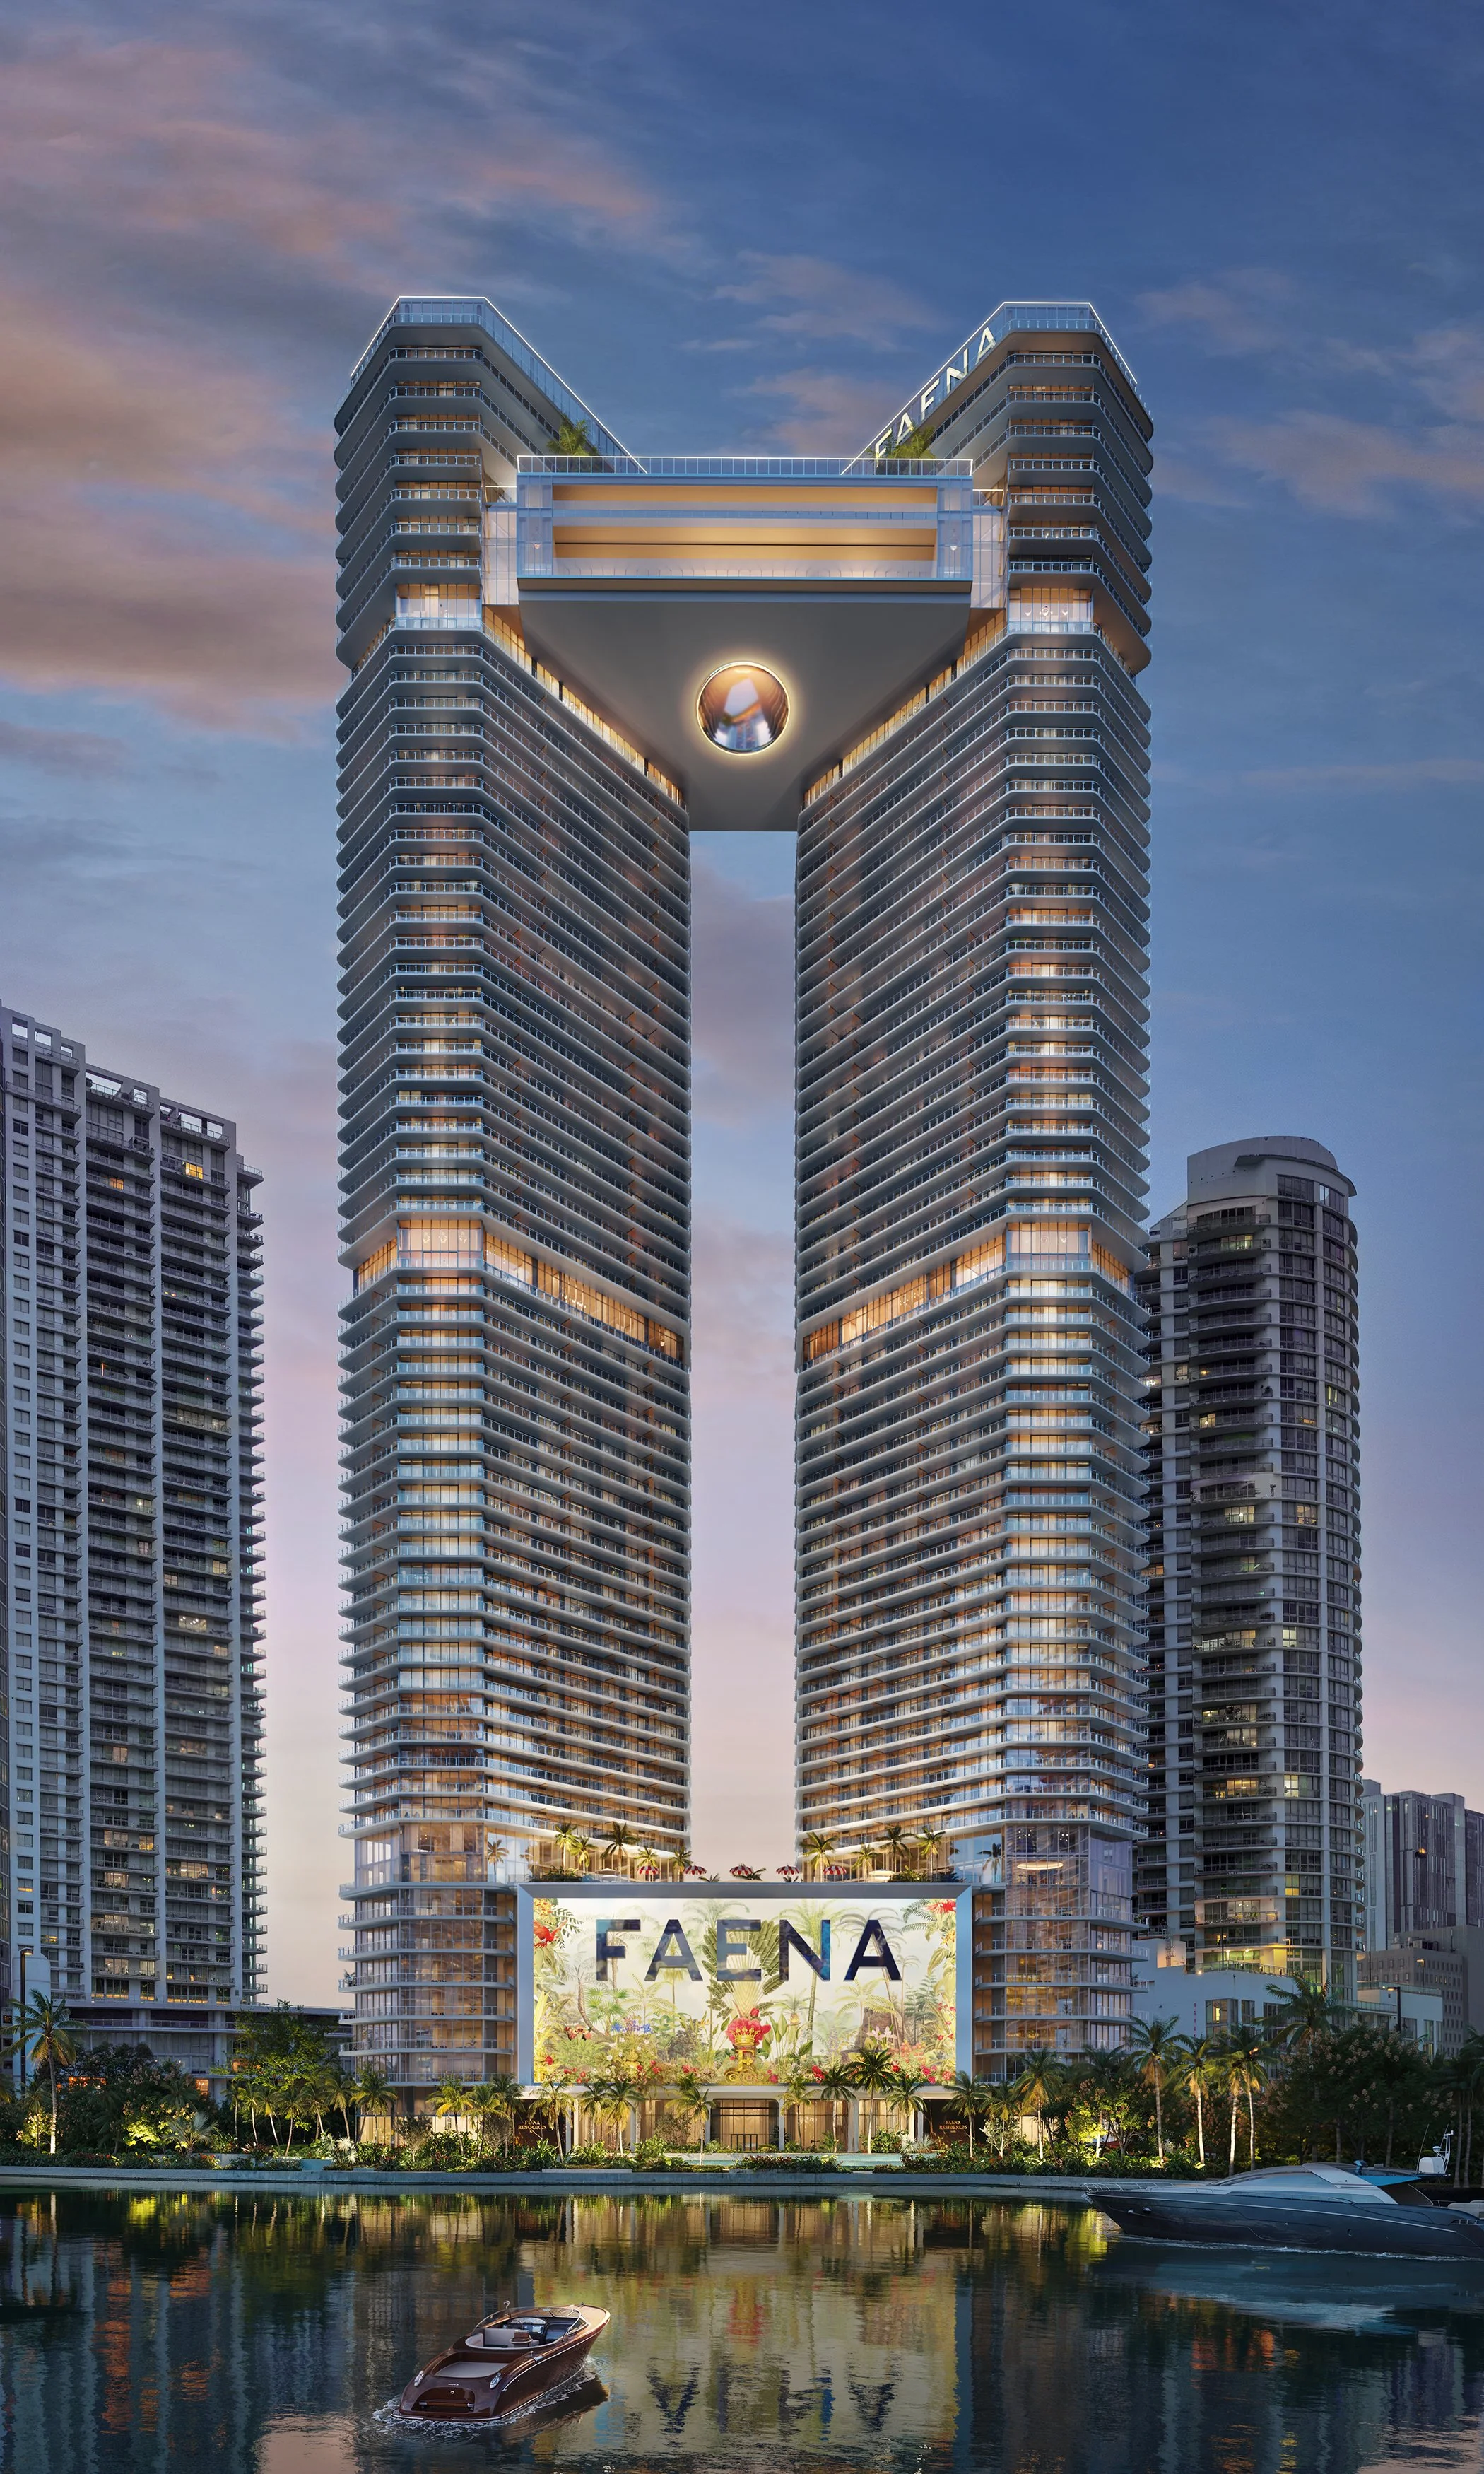
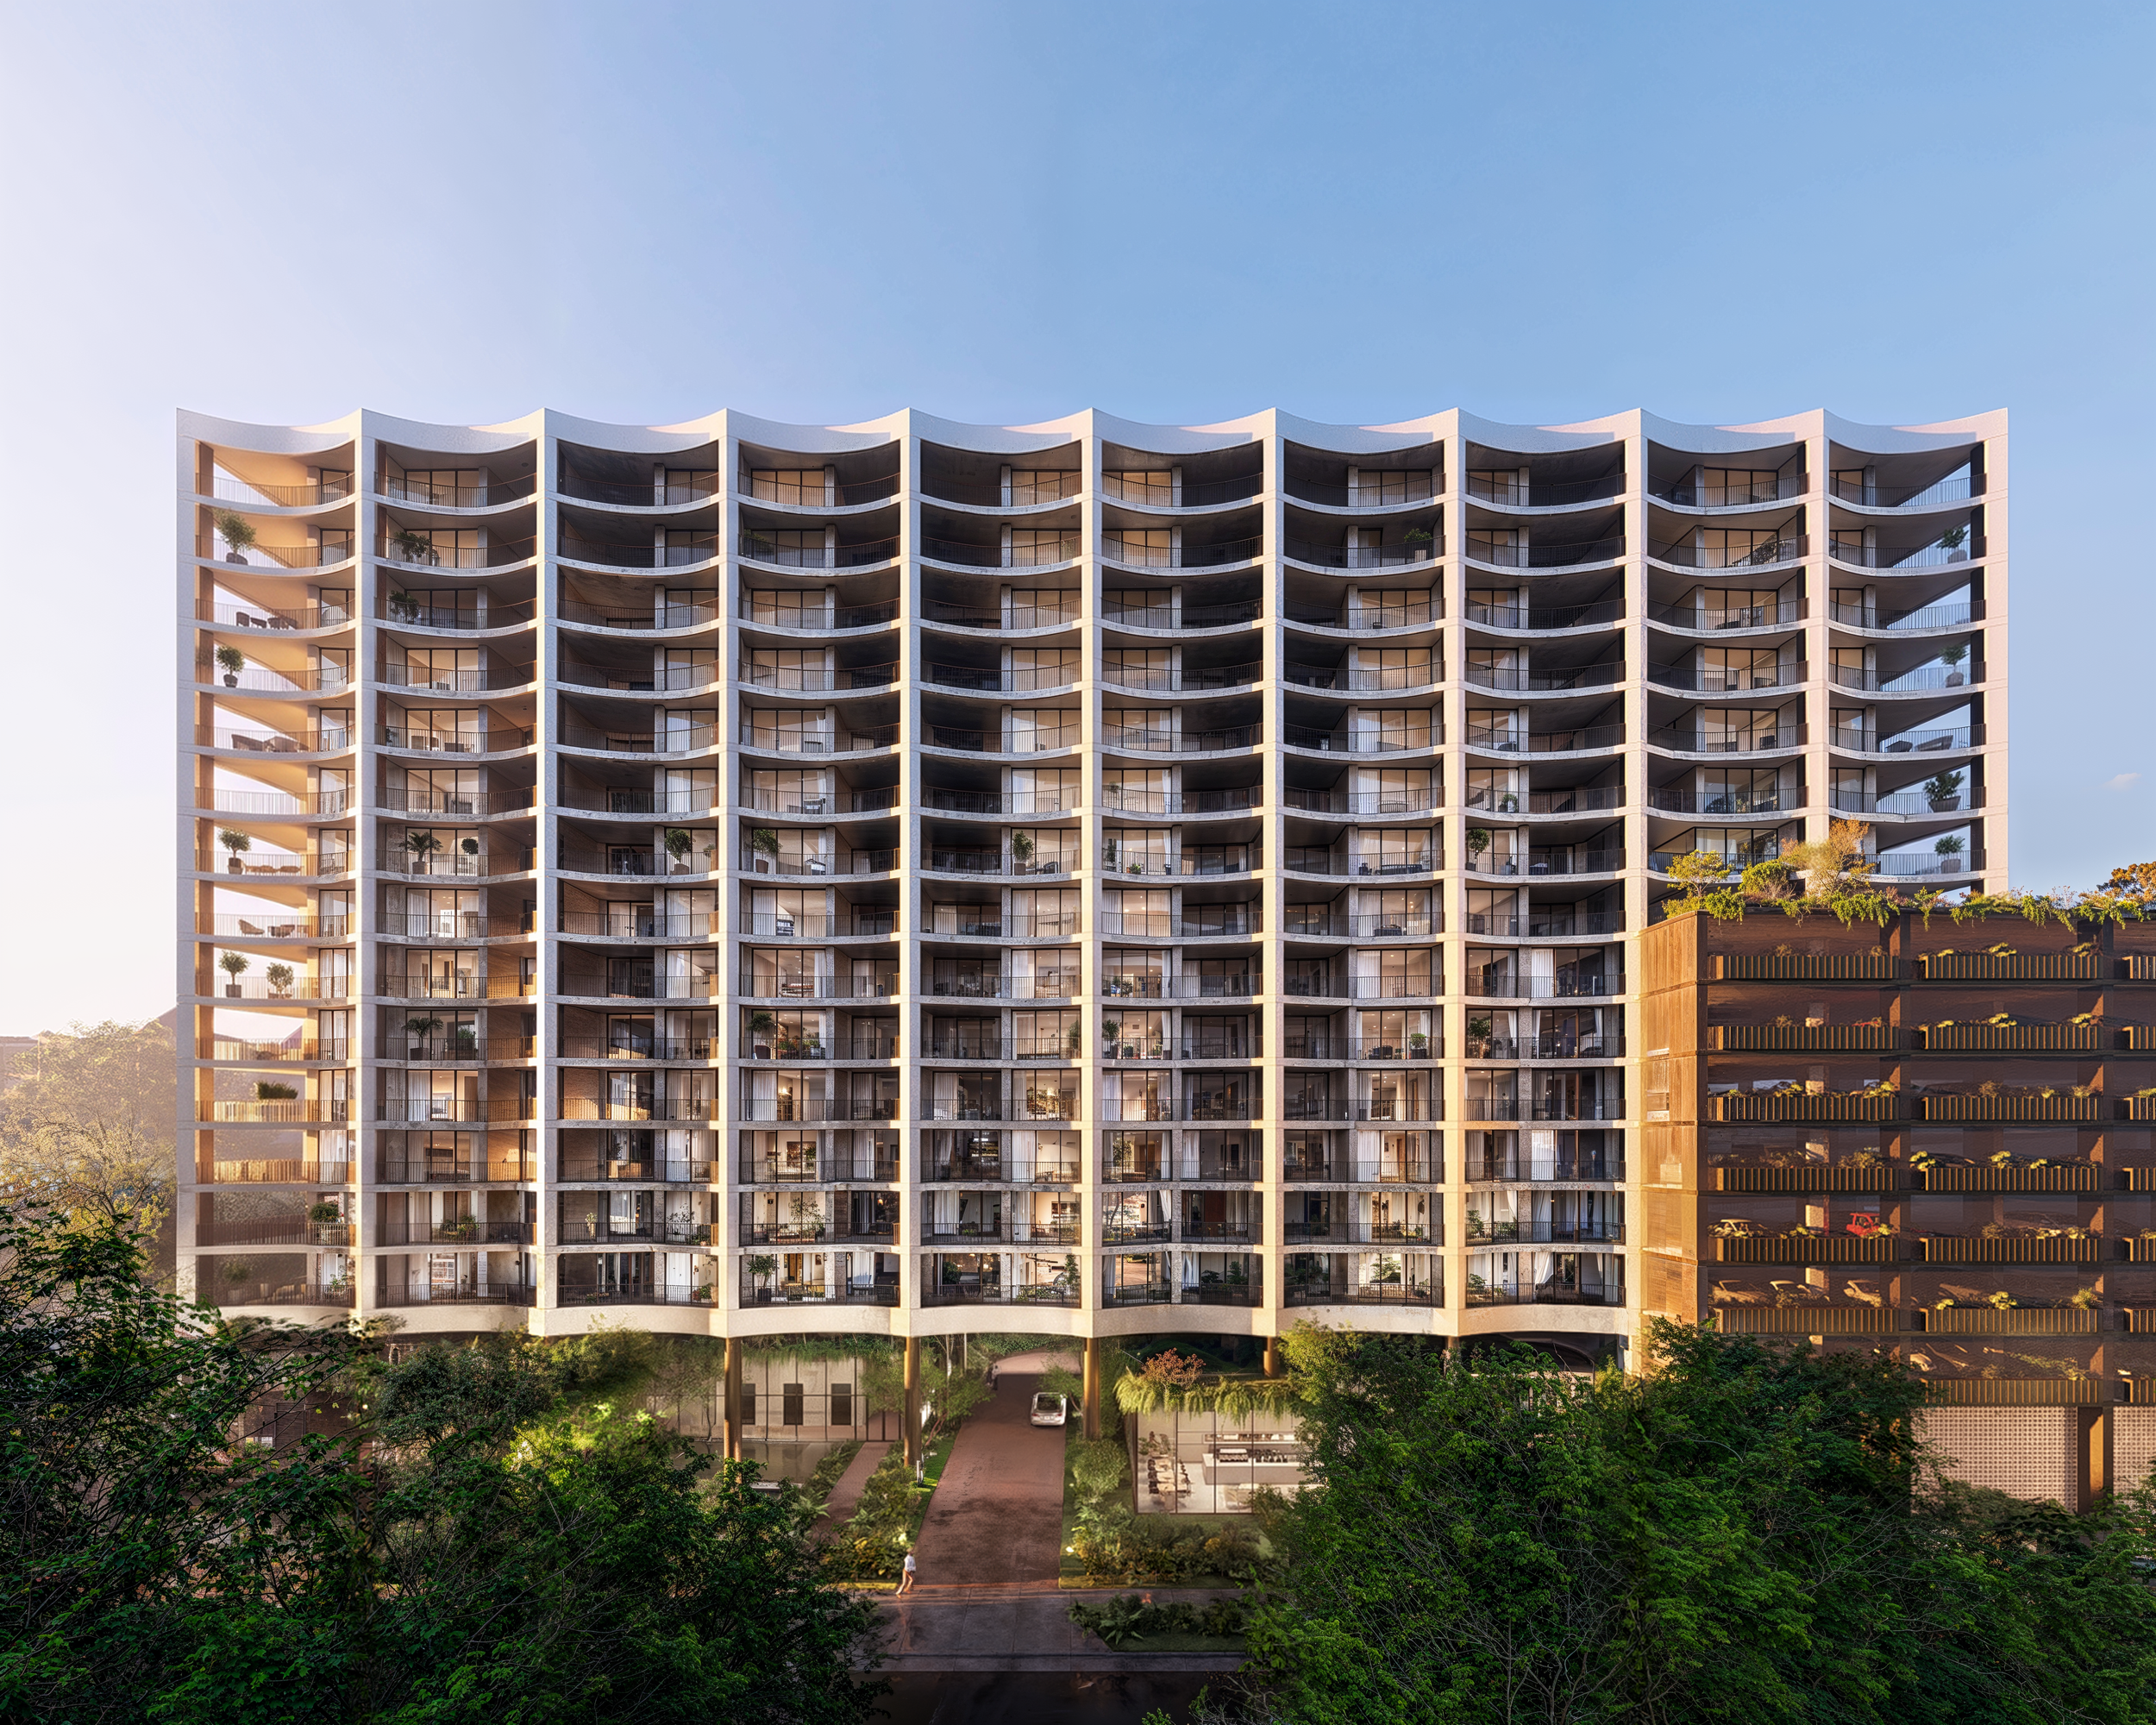
Mast Capital and BH Group have announced Raffles Residences Coconut Grove, the brand’s first standalone residential development, with 35 homes from $4.5 million and architecture by Brandon Haw.