
PMG and Greybrook Lock Down $142.3 Million Construction Loan for Society Wynwood
National investment, development, and asset management firm PMG, alongside partner Greybrook Realty Partners, has secured a $142.3 million construction loan for the 10-story Society Wynwood mixed-use project located at 2431 NW 2nd Ave. in Miami’s Wynwood Arts District.
National investment, development, and asset management firm PMG, alongside partner Greybrook Realty Partners, has secured a $142.3 million construction loan for the 10-story Society Wynwood mixed-use project located at 2431 NW 2nd Ave. in Miami’s Wynwood Arts District. The loan will provide financing for the development of the project, which commenced construction earlier this year.
Financing was provided by Pacific Western Bank and Square Mile Capital. In its second recent multifamily project with both lenders and sixth overall transaction with the duo, PMG was represented internally by Andrew Warman, Lowell Plotkin and Jonathan Blank.
“We are thrilled to expand our relationship with these top lenders beside our partners at Greybrook to create a premier living and entertainment destination on the most prominent block in Wynwood,” said Ryan Shear, Managing Partner at PMG. “Miami and the Wynwood market are close to our hearts as a team of passionate locals. With the incredible success we’ve experienced at Society Las Olas in Fort Lauderdale, and Society Biscayne slated to open in early 2022 in Downtown Miami, Society Wynwood will be the third social apartment community in South Florida under our rapidly expanding Society Living national brand. Society Wynwood will provide a community-driven living experience and attainably-priced housing that reflects the vibrant energy and positivity of the surrounding neighborhood.”
Slated for completion in Spring 2023, Society Wynwood will include 318 rental apartments and 50,210 SF of commercial space between the ground floor and rooftop. Scott Sherman’s Tricera Capital has a deal to acquire the commercial spaces upon completion of the project.
The development will offer a blend of traditional units with efficient layouts and “Rent-by-Bedroom” (co-living) options. Amenities will include a massive pool deck, co-working lab, modern gym and fitness studio, entertainment lounges, yoga lawn, craft food and beverage operations, smart package lockers, app-based keys, integrated retail space and more.
“Securing this construction loan for Society Wynwood further proves the strength of the Society Living portfolio and the appeal of social apartment communities,” Sami Mouaket, Director, U.S. Investments & Development at Greybrook Realty Partners. “Society Wynwood’s turnkey rental options, premium amenities and curated event programming deliver an attractive investment opportunity for investors and will provide outstanding quality of life for future residents.”
Launched in 2019, the national Society Living multifamily brand was created to address insatiable demand for reasonably priced rental communities close to urban centers, where modern neighbors can connect and thrive together. Urging residents to “Choose Happiness,” Society Living focuses on creating inspiring living spaces that foster personal growth within a culture of inclusivity and unity.
Existing Society Living developments include Society Las Olas in Downtown Fort Lauderdale, Florida, which opened in May 2020; Society Biscayne in Downtown Miami, slated to open in Q1 2022; Society Orlando, under construction in Downtown Orlando; and Society Denver, which was announced last month. Over 8,500 units are planned nationally including additional developments in Atlanta, Brooklyn and Nashville.
Icon of Palm Beach Shores Locks Down $25.16 Million Construction Loan
Icon Realty Capital, led by Anthony Shafer, has locked down a $25.16 million construction loan for Icon of Palm Beach Shores, an approved condo building coming to the north side of the Palm Beach inlet. The financing was arranged by the Washington-based Construction Loan Services II.
Icon Realty Capital, led by Anthony Shafer, has locked down a $25.16 million construction loan for Icon of Palm Beach Shores, an approved condo building coming to the north side of the Palm Beach inlet. The financing was arranged by the Washington-based Construction Loan Services II. Icon of Palm Beach Shores is located at 150-206 Inlet Way. Icon Realty Capital acquired the property in May 2021 for $6.27 million and plans to demolish the 70-year-old residential buildings which currently sits on the site.
Icon of Palm Beach Shores will feature 15 condo units which are expected to start at $2 million. Units feature direct water views from the living areas, modern design, high-end finishes and expansive balconies. Icon of Palm Beach Shores will be listed and marketed by Lauren Matthews of Douglas Elliman and Greg Forest of Sotheby’s International Realty.
For more information about Icon of Palm Beach Shores, private showings or purchasing/ leasing information please fill out the form below:
Terra Locks Down $44 Million In Financing For Publix-Anchored Retail Development In Pembroke Pines
Coconut Grove, FL-based Terra has locked down a $43.74 million in senior mortgage financing, provided by Thorofare Capital, Inc., an affiliate of alternative investment manager Thorofare LLC. The loan was issued to 16000 Pines Retail Investments, LLC, an entity managed by 16000 Pines Market.
Coconut Grove, FL-based Terra has locked down a $43.74 million in senior mortgage financing for 16000 Pines Market. The loan was provided by Thorofare Capital, Inc., an affiliate of alternative investment manager Thorofare LLC., and was issued to 16000 Pines Retail Investments, LLC, an entity managed by 16000 Pines Market. 16000 Pines Market is a 135,000 SF mixed-use retail development nearing completion in the City of Pembroke Pines in South Florida’s Broward County. The financing was arranged by Walker & Dunlop’s Keith Kurland, Jackson Sastri and Ian Hawk of the firm’s New York City capital markets group.
Terra will utilize the loan proceeds to finish construction, capitalize the TIs/LCs and carry the project until its stabilization. Construction of 16000 Pines Market’s first phase was completed earlier this year, with construction of phase two now getting underway and expected to deliver in 2022.
“Terra’s continued investment in Pembroke Pines reflects the City’s growing residential population and the high barriers to entry that exist for new commercial development,” said Terra CEO David Martin. “16000 Pines Market will meet mounting demand for lifestyle-oriented retail and unique food and beverage experiences, while offering an everyday amenity for neighboring residents and visitors.”
The key anchor tenant at 16000 Pines Market is 91-year-old Publix Super Markets, Inc., the largest and fastest-growing employee-owned supermarket chain in the United States. Additional co-anchors include national off-price department store retailer Burlington (NYSE: BURL), which operates 740 stores across 40 states and Puerto Rico with over 40,000 employees and a $20 billion market capitalization, as well as Crunch Fitness, a fitness club chain that has more than 300 franchise locations across the United States, Canada and Australia.
Felix Gutnikov, Thorofare’s principal and head of originations, said, “closing this construction-completion loan for a Publix-anchored retail asset in a desirable South Florida suburb comes on the heels of our Miami office opening and underscores the firm’s commitment to expand our geographic footprint in the Southeast.”
“This high-structured financing reflects our belief that well-designed grocery-anchored shopping centers, with sought-after tenants such as Publix, will continue to garner demand from institutional debt and equity capital sources,” said Thorofare’s principal and CIO Brendan Miller. “Executing a transaction with Terra will help continue to expand our presence in the Southeast as well as diversifying our loan portfolio with grocery-anchored assets, the most resilient, necessity-based retail property type.”
16000 Pines Market is situated on 13.2-acres with strong visibility along Pines Boulevard and Dykes Road, a major thoroughfare in the affluent suburb Pembroke Pines, which is part of the Ft. Lauderdale retail market and Southwest Broward retail sub-market. Additional tenants include Verizon, Regions Bank, a United States Postal Service branch, Jersey Mike’s Subs, Vivo Pizza & Pasta, FirstWatch Café, Cheddar’s and MD Now.
The Estate Companies Locks Down $76 Million Construction Loan For Soleste NoMi Beach In North Miami Beach
The Estate Companies, a subsidiary of Estate Investments Group (EIG), has locked down a $76 million construction loan for Soleste NoMi Beach apartments in North Miami Beach. The financing was provided by Bank OZK was arranged by Brian Gaswirth and Michael DiCosimo of JLL.
The Estate Companies, a subsidiary of Estate Investments Group (EIG), has locked down a $76 million construction loan for Soleste NoMi Beach apartments in North Miami Beach. The financing was provided by Bank OZK was arranged by Brian Gaswirth and Michael DiCosimo of JLL. The developer plans to break ground by the end of June after closing on the site in December 2020 for $13.1 million.
When complete, Soleste NoMi Beach will rise 23-stories and will feature 367 apartment units, 2,708 square feet of commercial space and 655 parking spaces. Amenities will feature a pool deck, spa, fitness center, co-working space and a landscaped rooftop garden.
Soleste NoMi Beach was approved in September 2020 and was designed by Form Group. The 1.78-acre site is located at 16395 Biscayne Blvd.
Kobi Karp-Designed Time Century Jewelry Center Secures $23.6 Million Construction Loan
Time Century Jewelry Center in Downtown Miami, led by real estate developer Yair Levy, has locked down a $23.6 million construction loan from City National Bank of Florida. The loan will fund phase 1 of the development which is scheduled to open in mid-2022.
Time Century Jewelry Center in Downtown Miami, led by real estate developer Yair Levy, has locked down a $23.6 million construction loan from City National Bank of Florida. The loan will fund phase 1 of the development which is scheduled to open in mid-2022. The construction crew is now working at installing a new HVAC system, building partition walls for the tenants, installing new plumbing and rewiring the electrical power system.
Time Century, formerly known as Metro Mall, is located at 1 NE First St. and spans 225,000 SF. The retail center is undergoing a $50 million renovation led by renowned architect Kobi Karp. With glass storefronts, soaring ceilings, elegant escalators and elevators, and state-of-the-art security, Time Century will be the first luxury high street retail property in Miami’s jewelry & diamond district.
Once completed, the jewelry center will offer four floors of luxury jewelry retail and wholesale space as well as four additional floors of offices. A large three-story atrium with newly designed escalators and computerized directories will seamlessly direct customers throughout all levels. Most tenants will have unobstructed signage viewable from the main floor. Customers will also benefit from Time Century’s valet parking service and the several newly-built public parking garages steps away from the building.
The wholesale retail space currently available ranges from 500 SF to 2,000 SF with rental rates ranging from $65 to $150 PSF.
For more information about commercial leasing in Downtown Miami, private showings or availability/ pricing information please fill out the form below:
Melo Group Locks Down $99 Million Refinancing For Miami Plaza Apartment Tower In Downtown Miami
Melo Group has locked down a $99 million refinancing for its recently delivered transit-oriented Downtown Miami apartment tower, Art Plaza. The 36-story, 425-unit Art Plaza, which is located at 1500 Northeast Miami Plaza, is now 95% leased after Melo Group delivered the building in July 2020.
Melo Group has locked down a $99 million refinancing for its recently delivered transit-oriented Downtown Miami apartment tower, Art Plaza. The 36-story, 425-unit Art Plaza, which is located at 1500 Northeast Miami Plaza, is now 95% leased after Melo Group delivered the building in July 2020. The loan is a 10-year, interest-only loan financed by Freddie Mac and arranged by Peter Mekras of Aztec Group. The refinancing will be used to pay off a $62.7 million construction loan from BB&T which was funded in 2019.
Apartments at Miami Plaza feature expansive balconies with bay and city views, floor-to-ceiling sliding doors, energy-efficient tinted glass, European-style kitchen and bathroom cabinetry, granite countertops, double door refrigerators, stainless steel appliances, spacious living and dining rooms, imported ceramic tile and laminated wood flooring, and full-size washer and dryers. Residences at Miami Plaza apartments range from one- to three-bedrooms measuring between 700 to 1,400 square feet. Monthly rental rates initially started at approximately $1,680 for one-bedroom units; $2,100 for two-bedroom units; and $2,640 for three-bedroom units.
Building amenities include a large 70-foot swimming pool, a fully-equipped fitness center, a café social lounge, 24-hour concierge/security, and a multi-level secured garage with valet service.
Miami Plaza marks the fourth multifamily development, and sixth tower, that Melo Group has delivered in the Arts & Entertainment District since 2016 and completes the final phase of the firm’s plan to bring more than 2,300 transit-oriented rental units to the growing neighborhood. The firm’s previously completed developments in the area, all of which are clustered around the Miami-Dade Metromover School Board Station within a few blocks of each other, include the 497-unit Melody Tower, which delivered in 2016; the two-tower 710-unit Square Station, which delivered in 2018; and most recently, the two-tower 667-unit Art Plaza, which delivered in 2019. Melo Group is also developing Downtown 5th at 55 NE 5th Ave, an apartment community with 1,042 rental units spread over two 51-story towers in nearby Downtown Miami.
Aztec Group Arranges $15 Million Sale Of Miami Gardens Office
Aztec Group, Inc., a Miami-based real estate investment and merchant banking firm, has announced that Peter Mekras and Brell Tarich have arranged the $15,350,000 sale of Lincoln Square, a 116,560 square-foot suburban office complex.
Aztec Group, Inc., a Miami-based real estate investment and merchant banking firm, has announced that Peter Mekras and Brell Tarich have arranged the $15,350,000 sale of Lincoln Square, a 116,560 square-foot suburban office complex located at 18405 NW 2nd Avenue in Miami Gardens, Florida. Lincoln Square was built in 1980 and features two 5-story office buildings on 5.78-acres with frontage on SR-7 (441) just one mile north of the Golden Glades Interchange.
Aztec Group was engaged by Miami-based, TM Real Estate Group to run a broad marketing process to sell the property at the end of 2020. After sourcing and underwriting numerous competitive offers, Aztec assisted the Seller with selecting the buyer, Preminger Investments. The buyer assumed the existing $11,500,000 CMBS loan secured by the property with a fixed interest rate of 4.86% and approximately 8 more years of amortizing term.
“Despite the economic impacts of Covid-19, market concerns with current office utilization, and the added challenge of a buyer assuming a CMBS loan, Aztec and TM Real Estate Group were able to execute a successful sale process for Lincoln Square.” said Peter Mekras, President of Aztec Group. TM Real Estate Group sold Lincoln Square and the adjacent Washington Square for a combined $21,450,000 after acquiring the two-property portfolio, five years ago for a combined $12,600,000.
The Aztec Group team remains active in the Florida Real Estate Market with over $385 million in recently completed sales, joint venture equity, and debt financing transactions for rental apartment communities, retail, hospitality, office, senior housing, and land.
OKO Group and CAIN International Lock Down $128.3 Million Construction Loan For Una Residences
OKO Group and Cain International have secured $128.3 million in construction financing for Una Residences. The senior debt, which was provided by Bank OZK, will fund the ongoing development of the 47-story luxury condo tower, which broke ground in May 2020 and has over $75 million in sales over the past four months.
OKO Group and Cain International have secured $128.3 million in construction financing for Una Residences. The senior debt, which was provided by Bank OZK, will fund the ongoing development of the 47-story luxury condo tower, which broke ground in May 2020 and has over $75 million in sales over the past four months.
The Walker & Dunlop team led by Senior Managing Directors & Co-Heads of New York Capital Markets Keith Kurland, Aaron Appel, and Adam Schwartz along with Managing Director Michael Diaz and Director Sean Bastian represented the developers in the transaction. Weil Gotshal & Manges served as counsel for the sponsor/developer, while King & Spaulding served as counsel for Bank OZK.
Una Residences sits on one of the last developable parcels of waterfront land in Brickell in the South Brickell enclave at 174 SE 25th Road and will become the first waterfront residential tower to deliver in the neighborhood in over a decade upon its completion in 2023. The tower is being developed by a partnership between OKO Group, the luxury development group helmed by international real estate mogul Vladislav Doronin, and Cain International, a privately held investment firm with over $6.3 billion in real estate equity, debt, and leisure-focused investments.
“Miami’s increasing global appeal is drawing families to live and businesses to invest in high quality real estate, particularly rare and exclusive offerings such as Una Residences; one of the last opportunities to buy a waterfront property in one of Miami’s most desirable neighborhoods,” said Vladislav Doronin, Chairman and CEO of OKO Group. “We are seeing this trend of moving to Miami accelerate at an unprecedented rate, attracted by the many benefits including its sunny weather, quality of life, status as a global destination and its tax incentives. As construction progresses on site at Una Residences, we anticipate a beneficial and successful relationship with all parties involved in this project.”
Una Residences was designed by Adrian Smith + Gordon Gill (AS+GG) and the tower will offer 135 spacious two-to-five bedroom condominiums with unobstructed views of the Atlantic Ocean, Biscayne Bay, and city skyline. Residences are priced from $2 million to $7.4 million, with two ultra-exclusive penthouses priced up to $21.6 million.
"We firmly believe the Miami market is well-positioned for future growth as a global gateway city, with continued demand for new residential property coming from both foreign and domestic buyers. Closing this financing with Bank OZK is a significant milestone for Una Residences and for the broader Brickell residential market," said Jonathan Goldstein, CEO of Cain International. "With its unique position overlooking Biscayne Bay, close proximity to Key Biscayne, Brickell and Coconut Grove, and access to incredible lifestyle amenities, Una Residences is truly one-of-a-kind and we look forward to advancing towards completion with our partners."
Amenities include three swimming pools, a children’s splash-pad area and playroom, a movie theater, an Aman Resort-inspired spa and steam room, a state-of-the-art fitness center featuring yoga and personal training facilities, onsite dining, and more. Una’s amenities will also extend beyond the property, as residents will receive exclusive membership access to the Grand Bay Club on the beachfront of Miami’s Key Biscayne.
“The fundamentals of the Una Residences project met the high standards Bank OZK consistently seeks in our credits – marquee real estate, strong market fundamentals and top-tier sponsorship,” stated Greg Newman, Managing Director of Originations for Bank OZK’s Real Estate Specialties Group. “OKO Group and Cain International are developing a best-in-class option in the Miami market, with amenities and an unrivaled setting that delivers an exceptional quality of life to residents. We appreciate the opportunity to participate in this project as the sole senior secured lender and look forward to a very successful execution.”
For more information about Una Residences, private showings or purchasing/ leasing information please fill out the form below:
Tricera Capital Locks Down $50.8 Million In Construction Financing For Mixed-Use Redevelopment The Press In West Palm Beach
Tricera Capital, led by Scott Sherman and Ben Mandell, have closed on $50.8 million in refinancing and construction financing for their mixed-use office and retail redevelopment The Press, located at 2751 South Dixie Highway in West Palm Beach.
Tricera Capital, led by Scott Sherman and Ben Mandell, have closed on $50.8 million in refinancing and construction financing for their mixed-use office and retail redevelopment The Press, located at 2751 South Dixie Highway in West Palm Beach. The loan was provided by the Chicago-based Monroe Capital. Tricera Capital was represented by Jason Krane and Simon Ziff of Ackman-Ziff Real Estate Group.
Tricera Capital acquired the former Palm Beach Post campus in March 2019 for $24 million. The redevelopment of the property is an example of creative adaptive re-use and expected to reinvigorate the city’s Dixie Highway corridor. The property was a former printing press and distribution facility and nearly all existing structures are to remain, including the Post’s office building and printing press. The project name is a nod to the Post’s legacy at the site.
The Press is divided into two components, The Shops at the Press, the 125,000 square foot retail component, and the adjacent Workspaces at the Press, the 140,000 square foot office component. Joseph’s Classic Market will serve as the retail anchor which was announced in February 2021 and the property will also feature a newly built Starbucks outparcel.
Rilea Group Teams Up With RealtyMogul To Raise Equity Via Crowdfunding For Mohawk At Wynwood
Rilea Group has teamed up with leading real estate crowdfunding platform RealtyMogul to raise equity for their new mixed-use Wynwood project, Mohawk at Wynwood. The crowdfunding campaign for the 12-story project, which is located at 56 NE 29th St., launched on April 5
Rilea Group has teamed up with leading real estate crowdfunding platform RealtyMogul to raise equity for their new mixed-use Wynwood project, Mohawk at Wynwood. The crowdfunding campaign for the 12-story project, which is located at 56 NE 29th St., launched on April 5 to RealtyMogul’s network of more than 200,000 qualified investors.
The Los Angeles-based RealtyMogul underwrites and reviews investments internally before opening them up to investors. Crowdfunding allows qualified investors to invest in institutional investments and larger development projects that they would otherwise have no access to.
The minimum crowdfunding investment for the Mohawk at Wynwood project is $35,000 and the estimated hold period for investors is 5 years. The targeted IRR is between 19.1% and 21.1% with a 2.26X target equity multiple.
A portion of the LP equity piece will be raised via crowdfunding as part of the $41 million total equity. 90%, $37 million, will come from LP’s and 10%, $4 million, is sponsored via the developer. A projected $62 million of debt rounds out the expected capitalization of the $103 million total development costs. Rilea group has the 1.5 acre property under contract for $22.33 million.
Mohawk at Wynwood will feature 225 apartment units and 22,000 square feet of retail. Amenities include a rooftop pool, bar, fitness center, residents lounge, dining room, children’s room, game room and dog park. The project was designed by Deforma Studio.
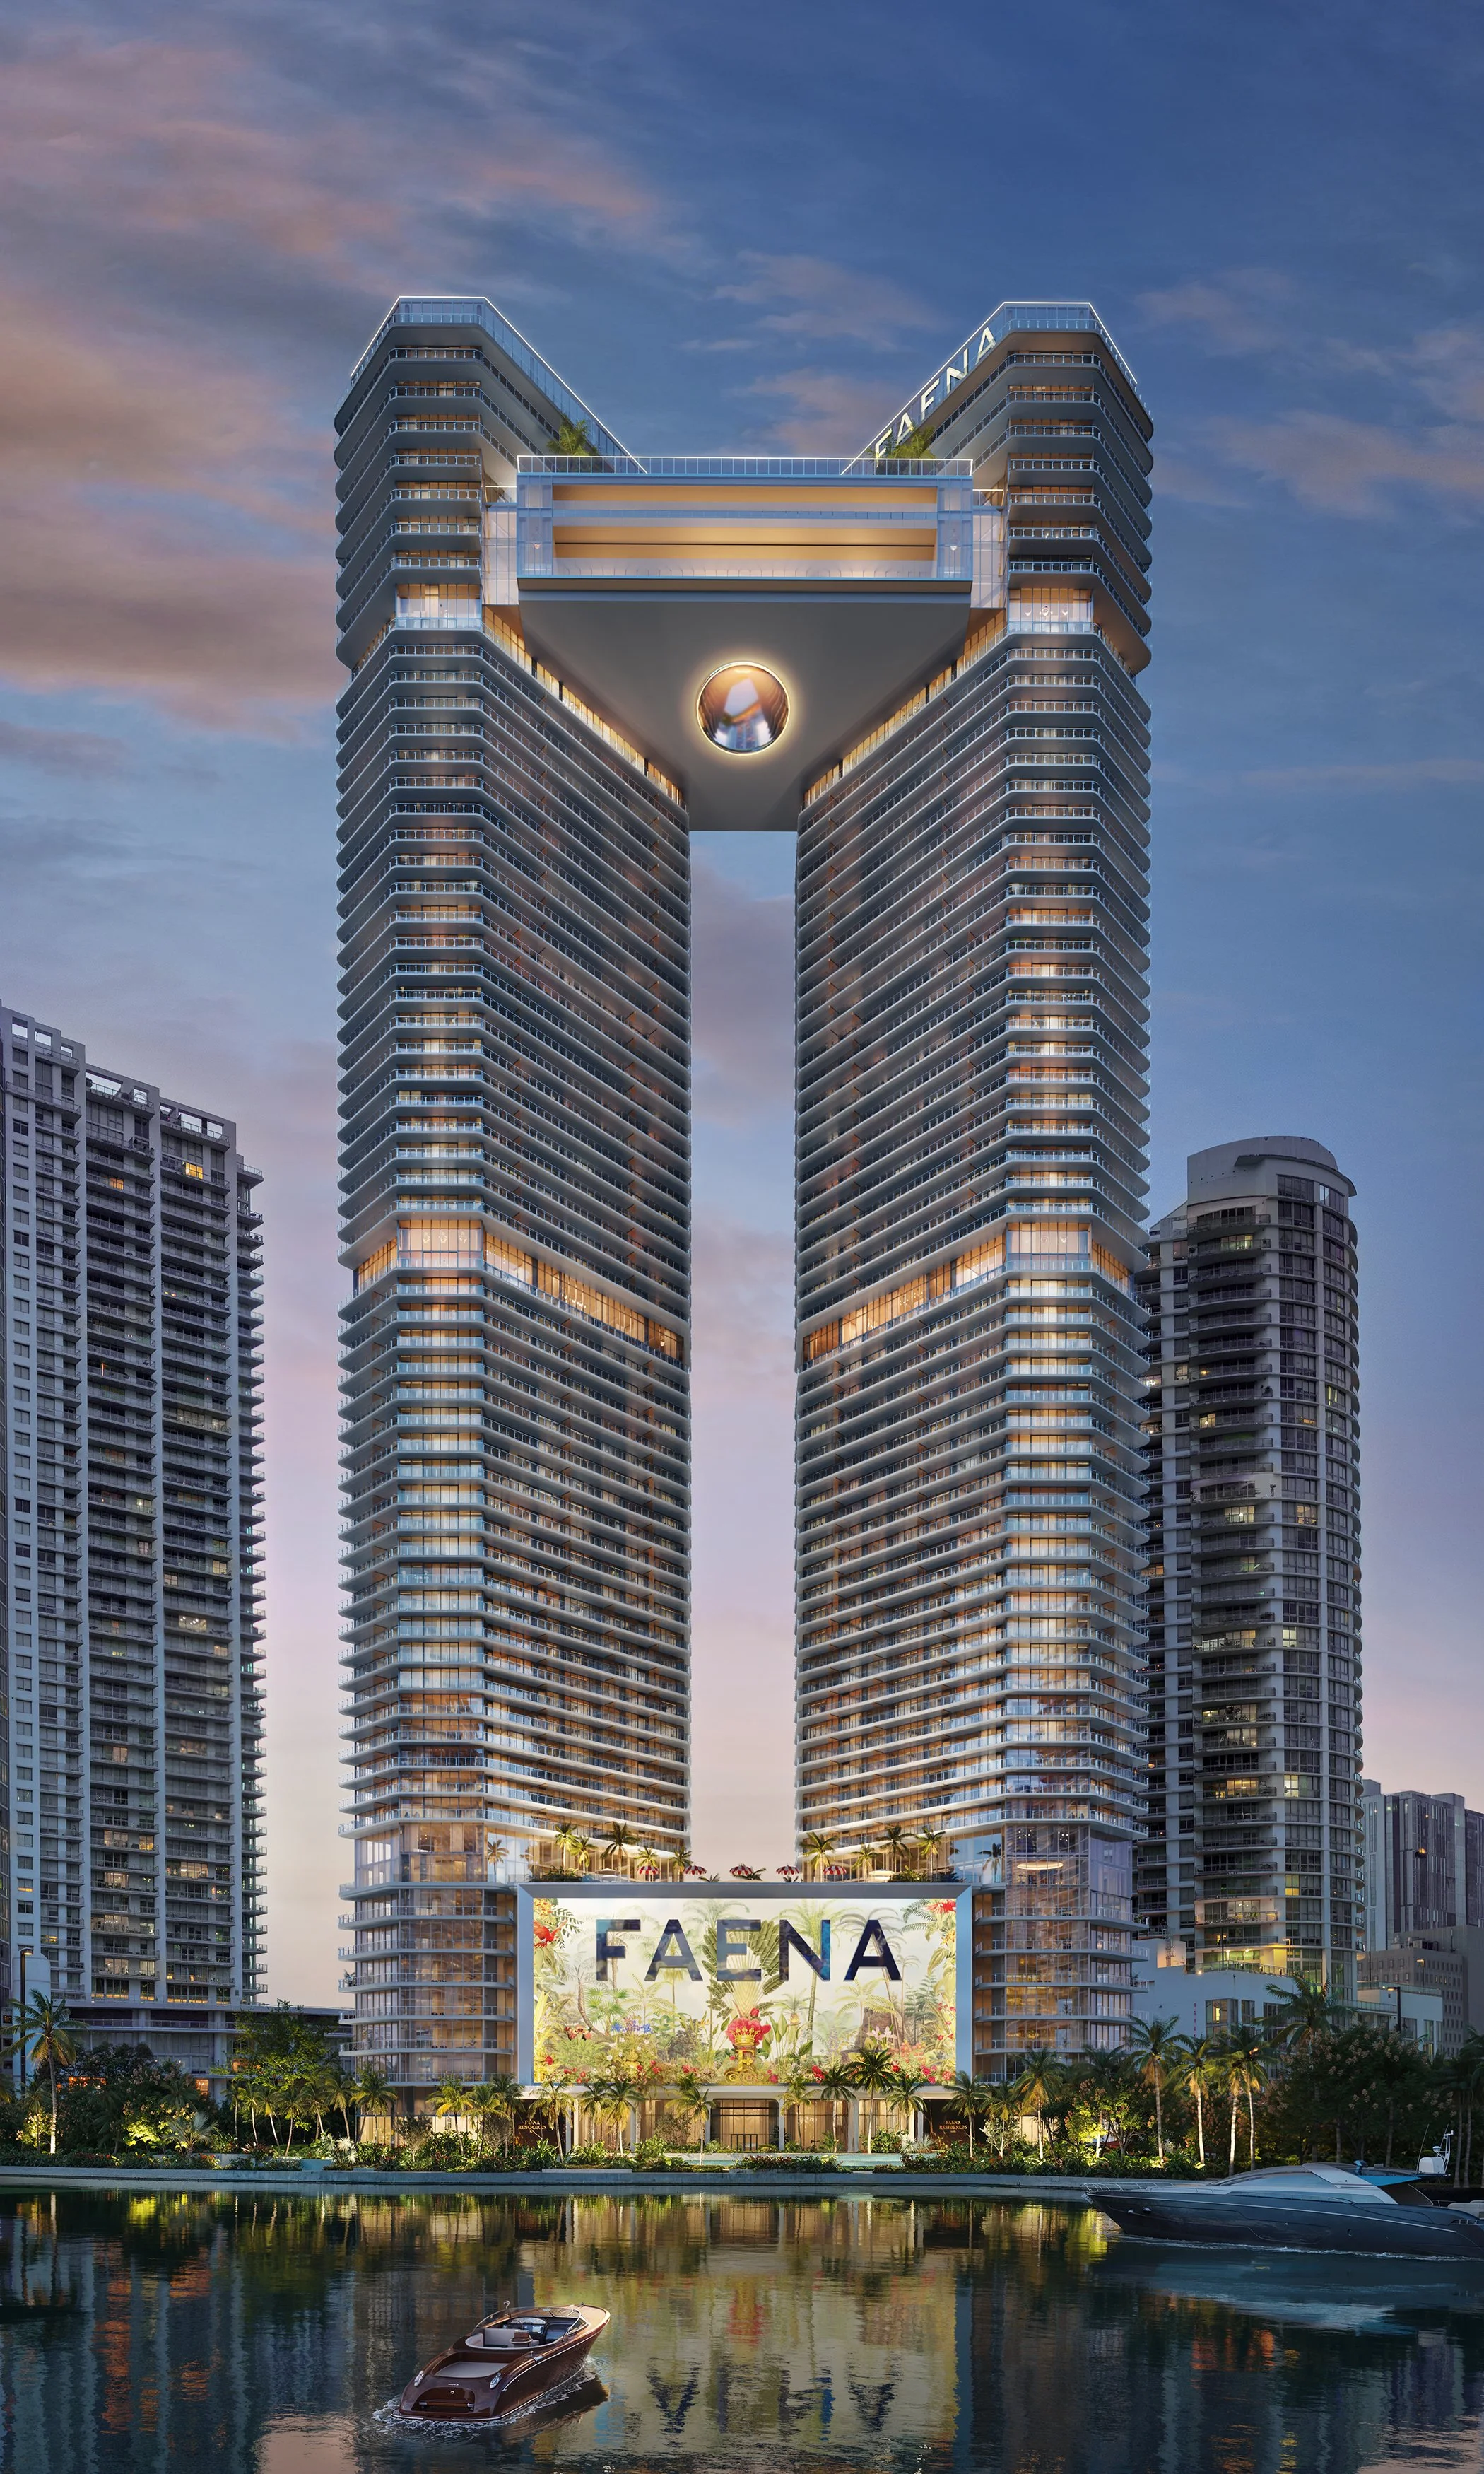
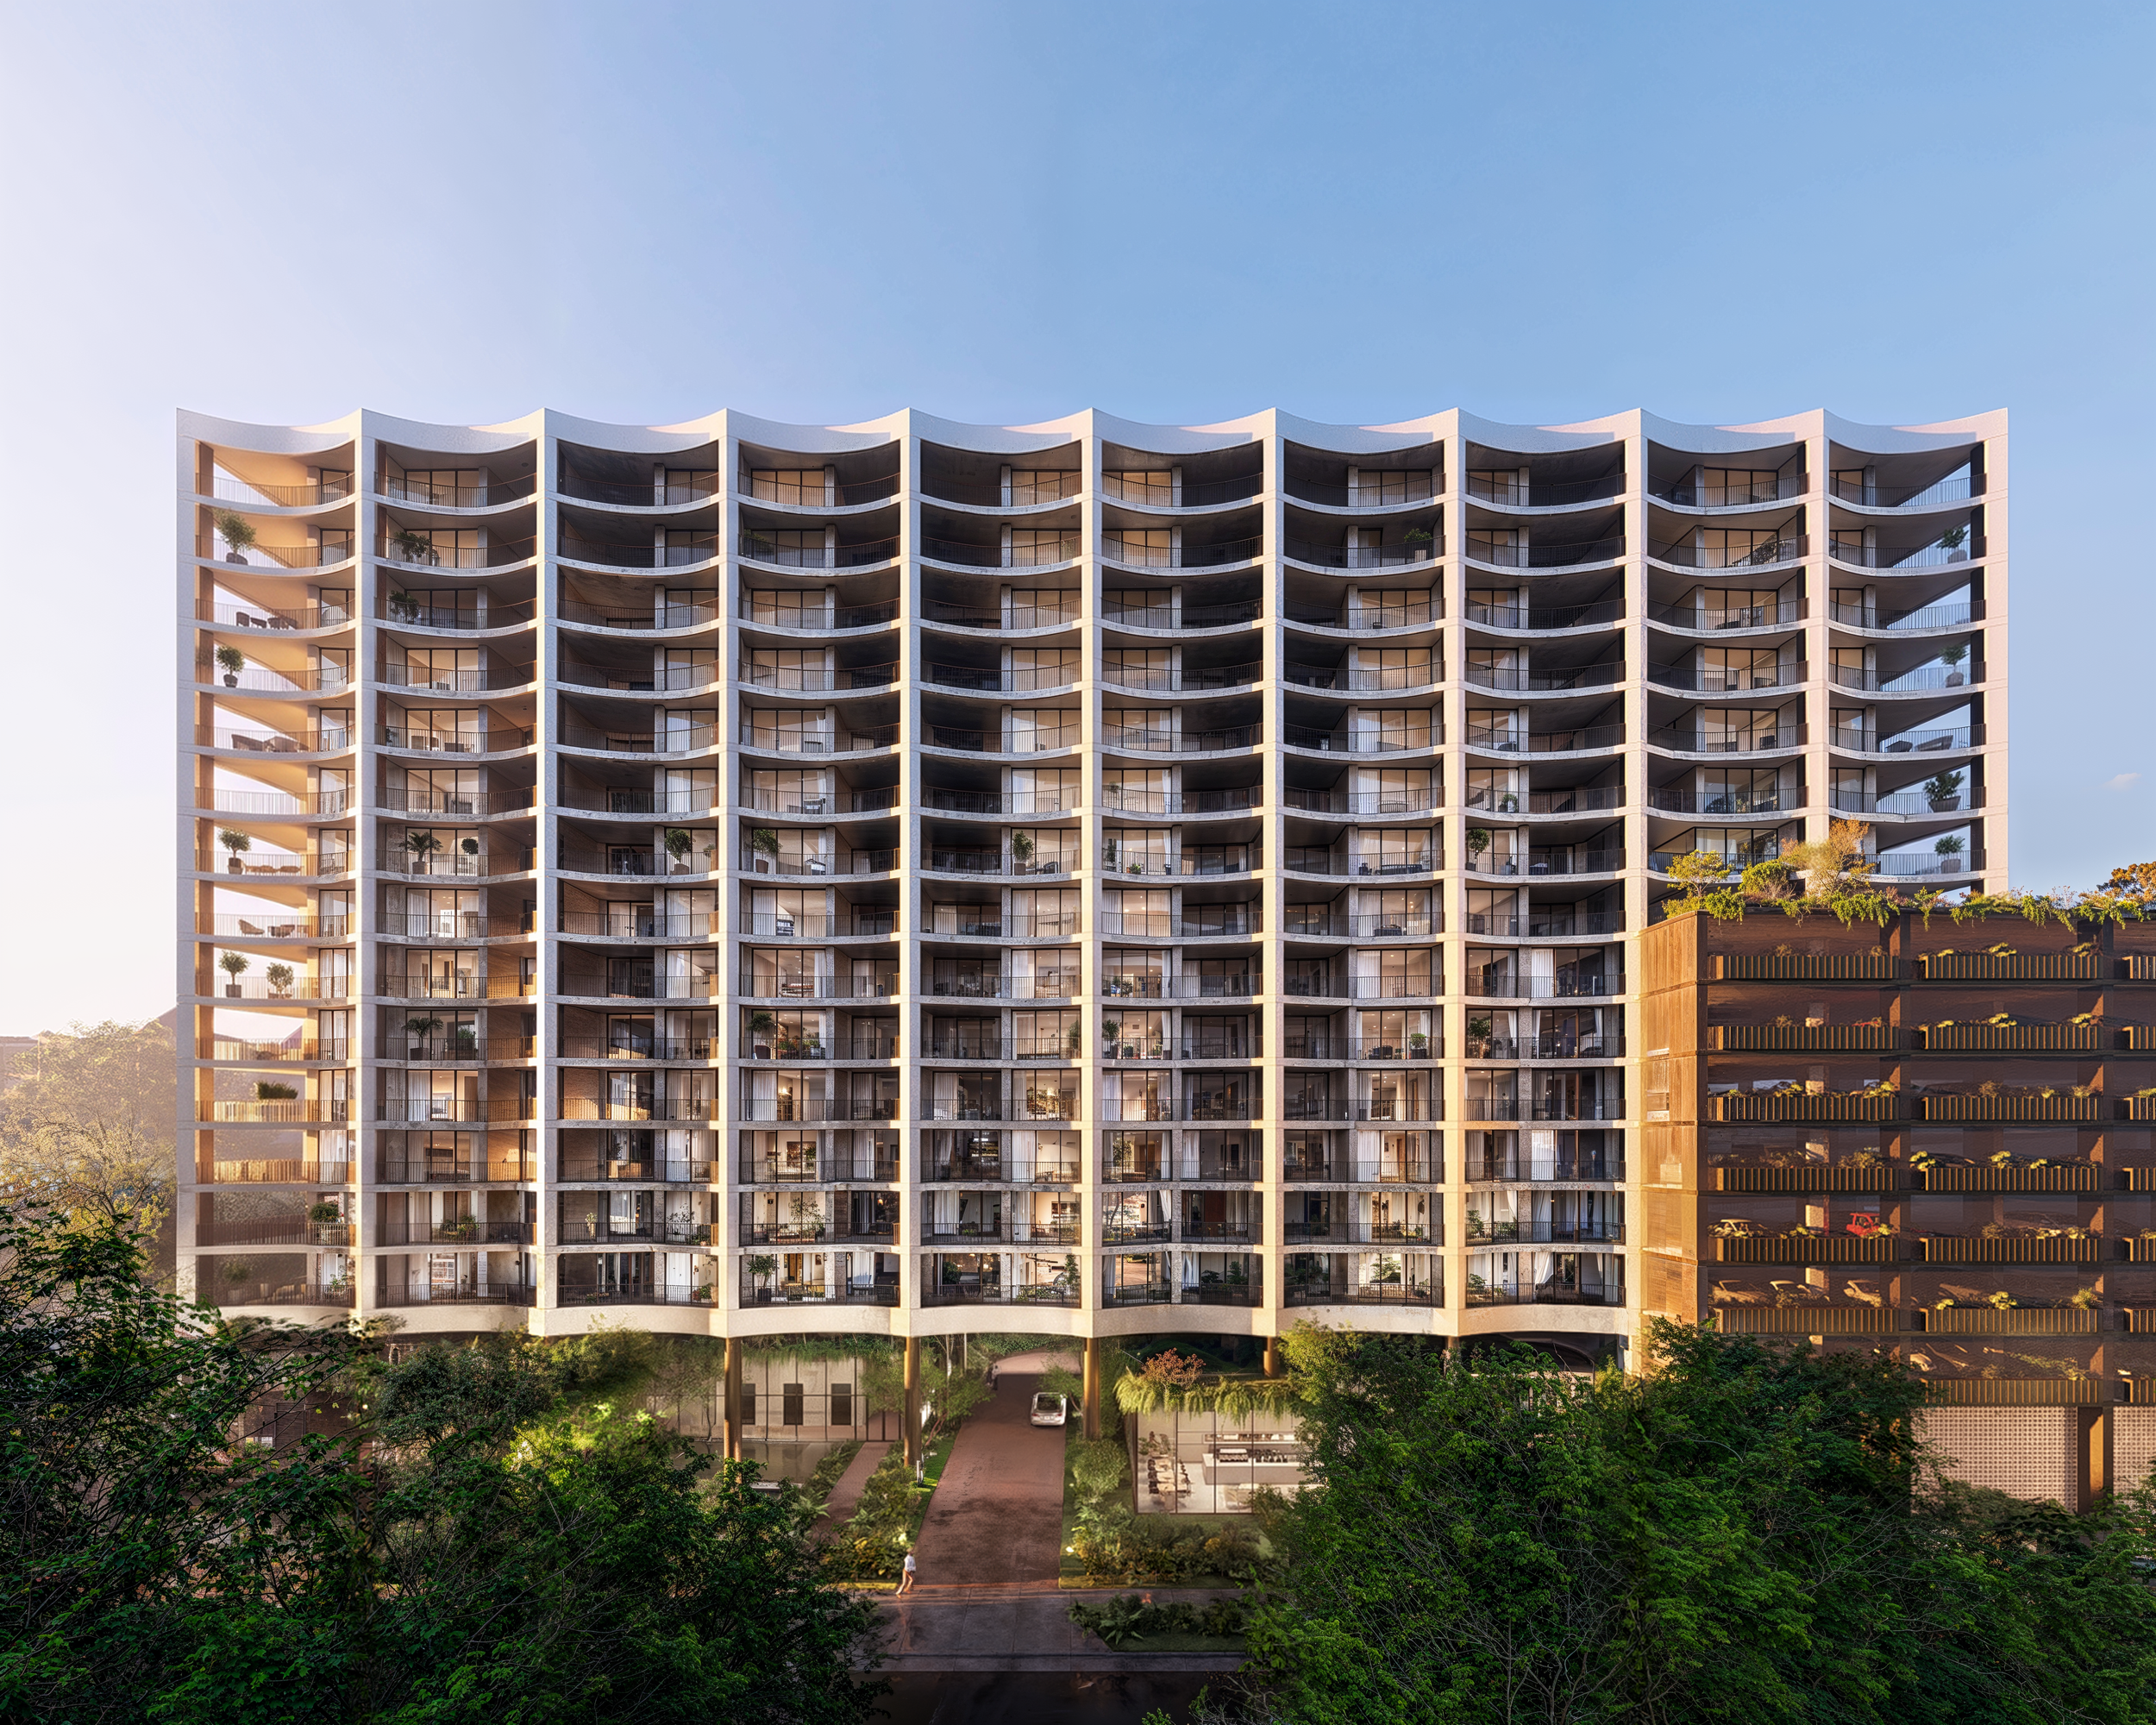
Mast Capital and BH Group have announced Raffles Residences Coconut Grove, the brand’s first standalone residential development, with 35 homes from $4.5 million and architecture by Brandon Haw.