
Andrew Kurnit of DWNTWN Realty Advisors Arranges $19 Million Construction Loan For Redwood National Properties Opa-Locka Project
Andrew Kurnit of DWNTWN Realty Advisors, the premier commercial real estate firm, arranged a $19 million construction loan from City National Bank of Florida for a townhome development in Opa-locka, Florida. Real estate investment firm Redwood National Properties, in a joint venture with David Burstyn of Winston Capital Partners, LLC, plans to build 112 four-bedroom, two-and-a-half-bathroom units on the 10-acre site.
Andrew Kurnit of DWNTWN Realty Advisors, the premier commercial real estate firm, arranged a $19 million construction loan from City National Bank of Florida for a townhome development in Opa-locka, Florida. Real estate investment firm Redwood National Properties, in a joint venture with David Burstyn of Winston Capital Partners, LLC, plans to build 112 four-bedroom, two-and-a-half-bathroom units on the 10-acre site located at 1719 NW 143rd St.
The venture closed on the site acquisition concurrently with the construction financing on August 27th. Redwood is led by Brian A. Sidman of BAS Holdings Investments, LLC. Kurnit was engaged by BAS to provide financial analysis and capital advisory services for the project.
“Miami’s affordable housing crisis is extensively documented, and four-bedroom units are amongst the scarcest,” said Kurnit, head of DWNTWN’s capital advisory practice. “The project is unique for Miami as it contains enough acreage for townhome development, is both gated and lakefront and in close proximity to the region’s main employment and leisure drivers.”
The development will consist of 23 separate four and five-unit buildings and the developers intend to target Section 8 Housing Choice Voucher Holders in its leasing strategy. The community will be gated, lakefront and well-appointed, all rarities for affordable and workforce housing. Each unit will feature contemporary finishes, high-impact windows and lake views. Coastland Construction will be the builder. Redwood’s site is located within an existing 59-unit townhome development called The Mirage at Sailboat Cove, which was initially constructed in 2007.
The project is expected to begin delivering units in mid-2021, with full completion expected in early 2022.
Aston Martin Residences Miami Reveals New Renderings And Financing Options
G&G Business Developments has revealed new renderings and introduced a unique way of financing their new property at Aston Martin Residences Miami. Created to simplify the buying process, clients can enjoy a special payment plan developed with mortgage broker, Regal Group International.
G&G Business Developments has revealed new renderings and introduced a unique way of financing their new property at Aston Martin Residences Miami. Created to simplify the buying process, clients can enjoy a special payment plan developed with mortgage broker, Regal Group International.
After reviewing the market for over a year, Germán Coto, CEO of G&G Business Developments, and his team, saw an opportunity to innovate and enhance the buying experience by offering pre-construction deposit financing. This pioneering new program enables clients to finance their property from day one, providing buyers with greater freedom to manage their portfolio of investments and revenues.
“We’re redefining the Miami skyline with the new Aston Martin Residences, and now we’re redefining the way our valued customers can finance their new luxury homes,” says Germán Coto, CEO of G&G Business Developments. “At G&G we have a reputation for pursuing innovative projects with a clear vision to achieve exceptional results and increase customer satisfaction, and this is why we created an innovative financing option.”
The collaboration between Regal Group International, a trusted name in residential mortgage lending for more than 23 years, and G&G Business Developments, a leading global luxury real estate company, is good news for clients looking for a smart way to finance their new home.
“Buyers have the opportunity to purchase their home with a special long-term payment plan that will provide comfort and a smooth process for prospective clients,” says Juan Ayala, President of Regal Group International. “After the initial payment, the buyer will make equal monthly installments for the Term of the Loan. These installments are fixed from day one of signing the contract and for the full term of the loan. There is no prepayment penalty for the duration of the loan, and the client can cancel or change their lender without being penalized. Additional financing costs and commitment fees are not included and remain the buyer’s responsibility. This new financing plan is one of the first of its kind for a pre-construction luxury development.”
Regal Group International offers a highly personable approach, working with both parties, the prospective buyer and private investor, to ensure clients are supported throughout the sales process. Responsible for all financial and legal disclosures to the buyer pertaining to this financing, Regal Group International has developed a personalized and straightforward approval process, with a team of expert advisors on hand to ensure a smooth and stress-free transition to a new home at Aston Martin Residences.
Headquartered in Miami, G&G Business Developments was founded by CEO, Germán Coto. As the developer of Aston Martin Residences, the only Aston Martin real estate project in the world, G&G has a reputation for pursuing innovative projects with a clear vision that achieves exceptional results. This new financing offer is just one of the luxury services G&G has developed to make life easier for its high-level clients.
Aston Martin Residences, located at 300 Biscayne Boulevard Way in Miami, consists of 391 luxury residences and penthouses priced from the $970,000s to upwards of $50 million. The project is almost 60% sold, and construction is scheduled for completion in 2022.
For more information about Aston Martin Residences, private showings or purchasing/ leasing information please fill out the form below:
The Estate Companies Acquires Former Ramada Hotel in Hialeah for $15.25 Million
The Estate Companies (EIG), a leading developer of luxury multi-family projects throughout South Florida, has announced the $15.25 million acquisition of a five-acre site occupied by a former Ramada Hotel at 1950 W. 49th St. in Hialeah. The closing took place August 7th with $11.5 million in financing arranged by LV Lending, a local private lender.
The Estate Companies (EIG), a leading developer of luxury multi-family projects throughout South Florida, has announced the $15.25 million acquisition of a five-acre site occupied by a former Ramada Hotel at 1950 W. 49th St. in Hialeah. The closing took place August 7th with $11.5 million in financing arranged by LV Lending, a local private lender. The loan was facilitated by Camilo Niño, Ricardo Uribe and Alen Hernandez of LV Lending on behalf of 1950 Hialeah Holdings, LLC, an entity of The Estate Companies (EIG).
The non-operational 258-room Ramada hotel was originally constructed in 1970 with expansions completed in 1973, 1979 and 1988. The site is located directly adjacent to the Palmetto Expressway and the 103rd Avenue exit, providing extremely high visibility and accessibility.
“We are thrilled with this acquisition as it presents a rare opportunity to own all the fundamentals we look for in an asset,” stated Jeffrey Ardizon, principal, The Estate Companies. “The site is situated on arguably the City of Hialeah’s busiest corridor and main artery. The City of Hialeah is a market with very high barriers to entry, strong demographic support and close in proximity to some of the largest employment hubs in South Florida. In addition, the area offers great walkability with a variety of social, dining and entertainment options, including the Westland Mall, just a short distance away.”
Ardizon added, “The distressed hotel sector has created investment opportunities that firms like ours are ready and able to capitalize on. Not all sites are created equal, and buyers need to be nimble and flexible in order to ensure repurposed assets meet the current market demands.”
“We take our hats off to Camilo Niño and his team at LV Lending who arranged our financing in such a short period of time,” Ardizon added. “They were seamless in their execution and a pleasure to work with on this transaction.”
Owner of Bâoli, Massa Investment Group, Acquires Miami Beach's Paris Theater For $13 Million
Massa Investment Group has acquired Miami Beach’s Paris Theater, located at 550 Washington Ave., for $13 million; $508 per square foot. The Art Deco building, which was first built in 1935, spans 25,589 SF. The building was designed by architect Henry Hohauser and has operated over time as a cinema, adult movie house, nightclub and film studio.
Massa Investment Group has acquired Miami Beach’s Paris Theater, located at 550 Washington Ave., for $13 million; $508 per square foot. The Art Deco building, which was first built in 1935, spans 25,589 SF. The building was designed by architect Henry Hohauser and has operated over time as a cinema, adult movie house, nightclub and film studio. U2, Madonna, Jennifer Lopez, Christina Aguilera and Ricky Martin have all shot music videos at the theater. Big Time Productions was the seller after acquiring the Paris Theater for $975,000 in 1992 and first listing the property for $23 million in 2015. The transaction was financed with a $15.2 million loan provided by IberiaBank. Massa Investment Group is led by Mathieu Massa who is also the owner of Mr. Hospitality, the firm behind some of Miami’s most exclusive venues including Bâoli, Marion and El Tucan.
Image via Paris Theater
Goddard Investment Group Moves To Evict WeWork From South of Fifth Location
WeWork’s landlord at 429 Lenox Avenue, Goddard Investment Group, has moved to evict WeWork from their South of Fifth location at 429 Lenox Avenue in South Beach. The 43,500 SF building is fully leased by WeWork who skipped out on rent payments for April, May and June.
WeWork’s landlord at 429 Lenox Avenue, Goddard Investment Group, has moved to evict WeWork from their South of Fifth location at 429 Lenox Avenue in South Beach. The 43,500 SF building is fully leased by WeWork who skipped out on rent payments for April, May and June. An eviction notice reportedly alleges WeWork behind in excess of $650,000 in unpaid rent which must be paid by today or WeWork must vacate the property (July 7, 2020). WeWork first opened the South of Fifth location in early 2016 and is committed to the NNN lease until 2031. Goddard Investment Group financed 429 Lenox Ave. with a $23 million floating-rate loan issued by Granite Point Mortgage Trust, Inc. In Miami WeWork has other locations at 350 Lincoln Road, Brickell, Downtown Miami and Coral Gables.
Times have not been good to WeWork following its failed IPO in 2019. The coworking giant recently announced that it will being closing its first location to ever open in New York City and saw its valuation slashed from over $47 billion to $2.9 billion.
In May 2020, a group of WeWork’s members moved toward suing the co-working giant demanding that WeWork cease collecting rental fees. Many tenants had already requested rent relief, cancelled their leases or stopped paying, which put over $5.5 billion of CMBS loans backed by WeWork occupied properties at risk. Some of the CMBS loans back WeWork flagship locations in New York and San Francisco. WeWork has retained Newmark Knight Frank and JLL to try to renegotiate leases and negotiate concessions from landlords at some of their properties as the firm try to stave off a potential bankruptcy.
WeWork’s problems do not end there. Former CEO and co-founder Adam Neumann is reportedly under investigation for self-dealing by the New York State Attorney General. In addition, the Tokyo-based SoftBank led by Masayoshi Son and a special committee of WeWork board members have been locked in a legal battle after Softbank walked away from a $3 billion tender offer in April 2020 which was part of the $9.5 billion bailout package SoftBank signed with WeWork following WeWork’s failed IPO.
Governor Ron DeSantis Announces $250 Million In CARES Act Funding Allocated For Rental And Mortgage Assistance
Florida Governor Ron DeSantis has announced that the state will allocate $250 million in CARES Act funding to rental and mortgage assistance due to the COVID-19 pandemic shutdown. $120 million of the funds will be allocated to Florida Housing Finance Corp. which will provide rental assistance to households who live in affordable housing rentals within the Florida Housing Finance Corp. portfolio.
Florida Governor Ron DeSantis has announced that the state will allocate $250 million in CARES Act funding to rental and mortgage assistance due to the COVID-19 pandemic shutdown. $120 million of the funds will be allocated to Florida Housing Finance Corp. which will provide rental assistance to households who live in affordable housing rentals within the Florida Housing Finance Corp. portfolio and have been impacted by COVID-19. Qualified renters will be able to use the funds from July 2020 through December 2020. The announcement comes just days before Florida’s moratorium on evictions and foreclosures expires and a rush of evictions and foreclosures are expected in July.
An additional $120 million will be allocated for rental and homeowner assistance programs for those impacted by COVID-19 providing aid for rent assistance, mortgage payment assistance, downpayment and closing assistance, mortgage buy-downs, new construction, rehabs, emergency repairs and homeownership counseling. The final $10 million will be used for operating costs of the programs and technical assistance.
BGI Capital Announces Expansion to Palm Beach County and a New Managing Director, Gregory J. Laskody
BGI Capital will open a new Boca Raton office and expand its operation to Palm Beach County.
The Miami-based alternative lender and commercial real estate debt provider operates offices in Miami and New York, making this its third location. The new office will be located at 1900 Glades Road, Boca Raton, FL 33431.
Managing Partner Kenneth Baboun is leading BGI Capital’s expansion efforts into key markets, choosing to open a location in the county due to the demand the firm has experienced in the area and its strong network within the community.
In addition to the expansion, BGI Capital also welcomed Managing Director Gregory J.Laskody, CCIM to the firm. Gregory will serve as the firm’s primary Palm Beach County liaison spearheading its efforts to expand debt and capital solutions to a new client base.
With over 30 years of commercial real estate experience, Gregory has extensive expertise in investment sales, commercial real estate mortgage and investment banking, and valuation. Collectively, he has been involved in over $3 billion of commercial real estate transactions. Throughout his career, he has held production, leadership, and management positions with various companies in commercial real estate including Lee & Associates, Deloitte, Nomura Capital, Wells Fargo, Q10 Capital, Newmark Grubb Night Frank, and Colliers International.
“I believe that with my vertically-integrated experience in investment sales and CRE capital markets practice, combined with the firm’s network, will successfully meet our client’s investment objectives.” BGI was founded in Miami in 2013 and expanded into the Northeast in February of 2019 with the opening of its New York office, led by Managing Director Luis Tio. The firm’s presence in New York has led to securing multiple loans in Brooklyn, Astoria, the Bronx and Long Island City among others.In Miami, BGI Capital has played an integral role in the transformation of several Miami neighborhoods including Edgewater, Coral Gables, Brickell and Doral.
OKO Group's Vladislav Doronin Buys Fort Lauderdale Assemblage for $63 Million
A land trust controlled by OKO Group’s Vladislav Doronin, a billionaire real estate developer from Russia who is now has headquarters in New York and Miami, has acquired a 6.7 acre assemblage in Fort Lauderdale for $63 million.
A land trust controlled by OKO Group’s Vladislav Doronin, a billionaire real estate developer from Russia who is now has headquarters in New York and Miami, has acquired a 6.7 acre assemblage in Fort Lauderdale for $63 million. The acquisition was financed with a $33 million loan from Michael Dell’s MSD Partners. The assemblage is located just south of the New River and Las Olas Boulevard and includes 3 full blocks, 27 parcels, one of which includes the site of Dev Motwani’s 629 Residences, a 34-story, 251-unit apartment building at 629 SE 5th Ave. OKO Group is reportedly planning a pedestrian-oriented mixed-use development.
OKO Group has been on the move in South Florida. The news of the assemblage acquisition comes just one week after OKO Group announced that Vanessa Grout was appointed CEO of the newly formed OKO Real Estate which would oversee the OKO Group’s sales and marketing. OKO Group also recently broke ground on Una Residences in Brickell and announced the Aman Hotel & Residence in Miami Beach’s Faena District. Construction continues on the 830 Brickell office tower and Missoni Baia luxury condo building in Edgewater.
Grand Station Partners Close On $53 Million Loan For Luxury Rental Tower Project
Grand Station Partners closed on a $53 million loan in early March for Grand Station Tower located at 40 NW 3rd Street in Downtown Miami. ROVR Development, which is led by Oscar Rodriguez and Ricardo Vadia, set-up Grand Station Partners and are building the 30-story, 300 unit building as a public-private partnership with Miami Parking Authority.
Grand Station Partners closed on a $53 million loan in early March for Grand Station Tower located at 40 NW 3rd Street in Downtown Miami. ROVR Development, which is led by Oscar Rodriguez and Ricardo Vadia, set-up Grand Station Partners and are building the 30-story, 300 unit building as a public-private partnership with Miami Parking Authority. Kayne Anderson affiliate Saperian Capital is the project’s lender.
The luxury rental tower, which will feature about 4,000 SF of retail space, will also expand the Courthouse Center Garage with 350 additional parking spaces. Grand Station Partners has a 99-year land lease on the site and has the option to extend the lease by an additional 50 years.
Michael Wolk Design Associates, a Miami-based design boutique specializing in residential, commercial, and hospitality interiors, along with furniture collections, designed the Grand Station’s interiors. The firm has had over 40 years of experience designing personalized, luxury interiors for their clients with a united effort to achieve client goals on-time and within budget.
The project’s interiors are inspired by a young urban vibe and were designed with a sophisticated look in mind. Michael Wolk Design Associates selectivity edited the color palette and used black, gray, and tobacco colors. Outdoor terraces were decorated with the furniture from the firm’s Biscayne Collection, which is manufactured by Pavilion. The tower’s social room has its own custom-designed triangle seating bench and award-winning “Gianni Lounge Chairs.”
Grand Station offers a gym, spa, and pool deck among its list of amenities. It is scheduled for completion early next year.
By Isabella Zimmermann
A Major Retailer Just Vacated Thor Equities' 663 Lincoln Road
COVID-19’s impact on commercial real estate is beginning to show its ugly wake. In late April Steve Madden reportedly notified Thor Equities, led by founder and CEO Joseph Sitt, that they would not be renewing their 2,269 SF lease at 663 Lincoln Road, which represents roughly 45% of the building.
COVID-19’s impact on commercial real estate is beginning to show its ugly wake. In late April Steve Madden reportedly notified Thor Equities, led by founder and CEO Joseph Sitt, that they would not be renewing their 2,269 SF lease at 663 Lincoln Road, which represents roughly 45% of the building. The vacancy is being marketed for a replacement tenant and the building is also listed for sale asking $17.5 million with Tony Arellano and Devlin Marinoff of DWNTWN Realty Advisors.
Thor Equities is reportedly working towards relief after falling delinquent on payments for a $7.3 million CMBS loan which is backed by the building. In 2012 Thor Equities paid $15 million for the 5,000 SF Lincoln Road-fronting retail building which was built in 1935. Pizza Rustica leases 1,700 SF in the building at the 667 Lincoln Road address.
Thor Equities’ Miami portfolio also includes the ground-floor retail space at 605 Lincoln Road as well as several properties in Wynwood and Miami Design District.
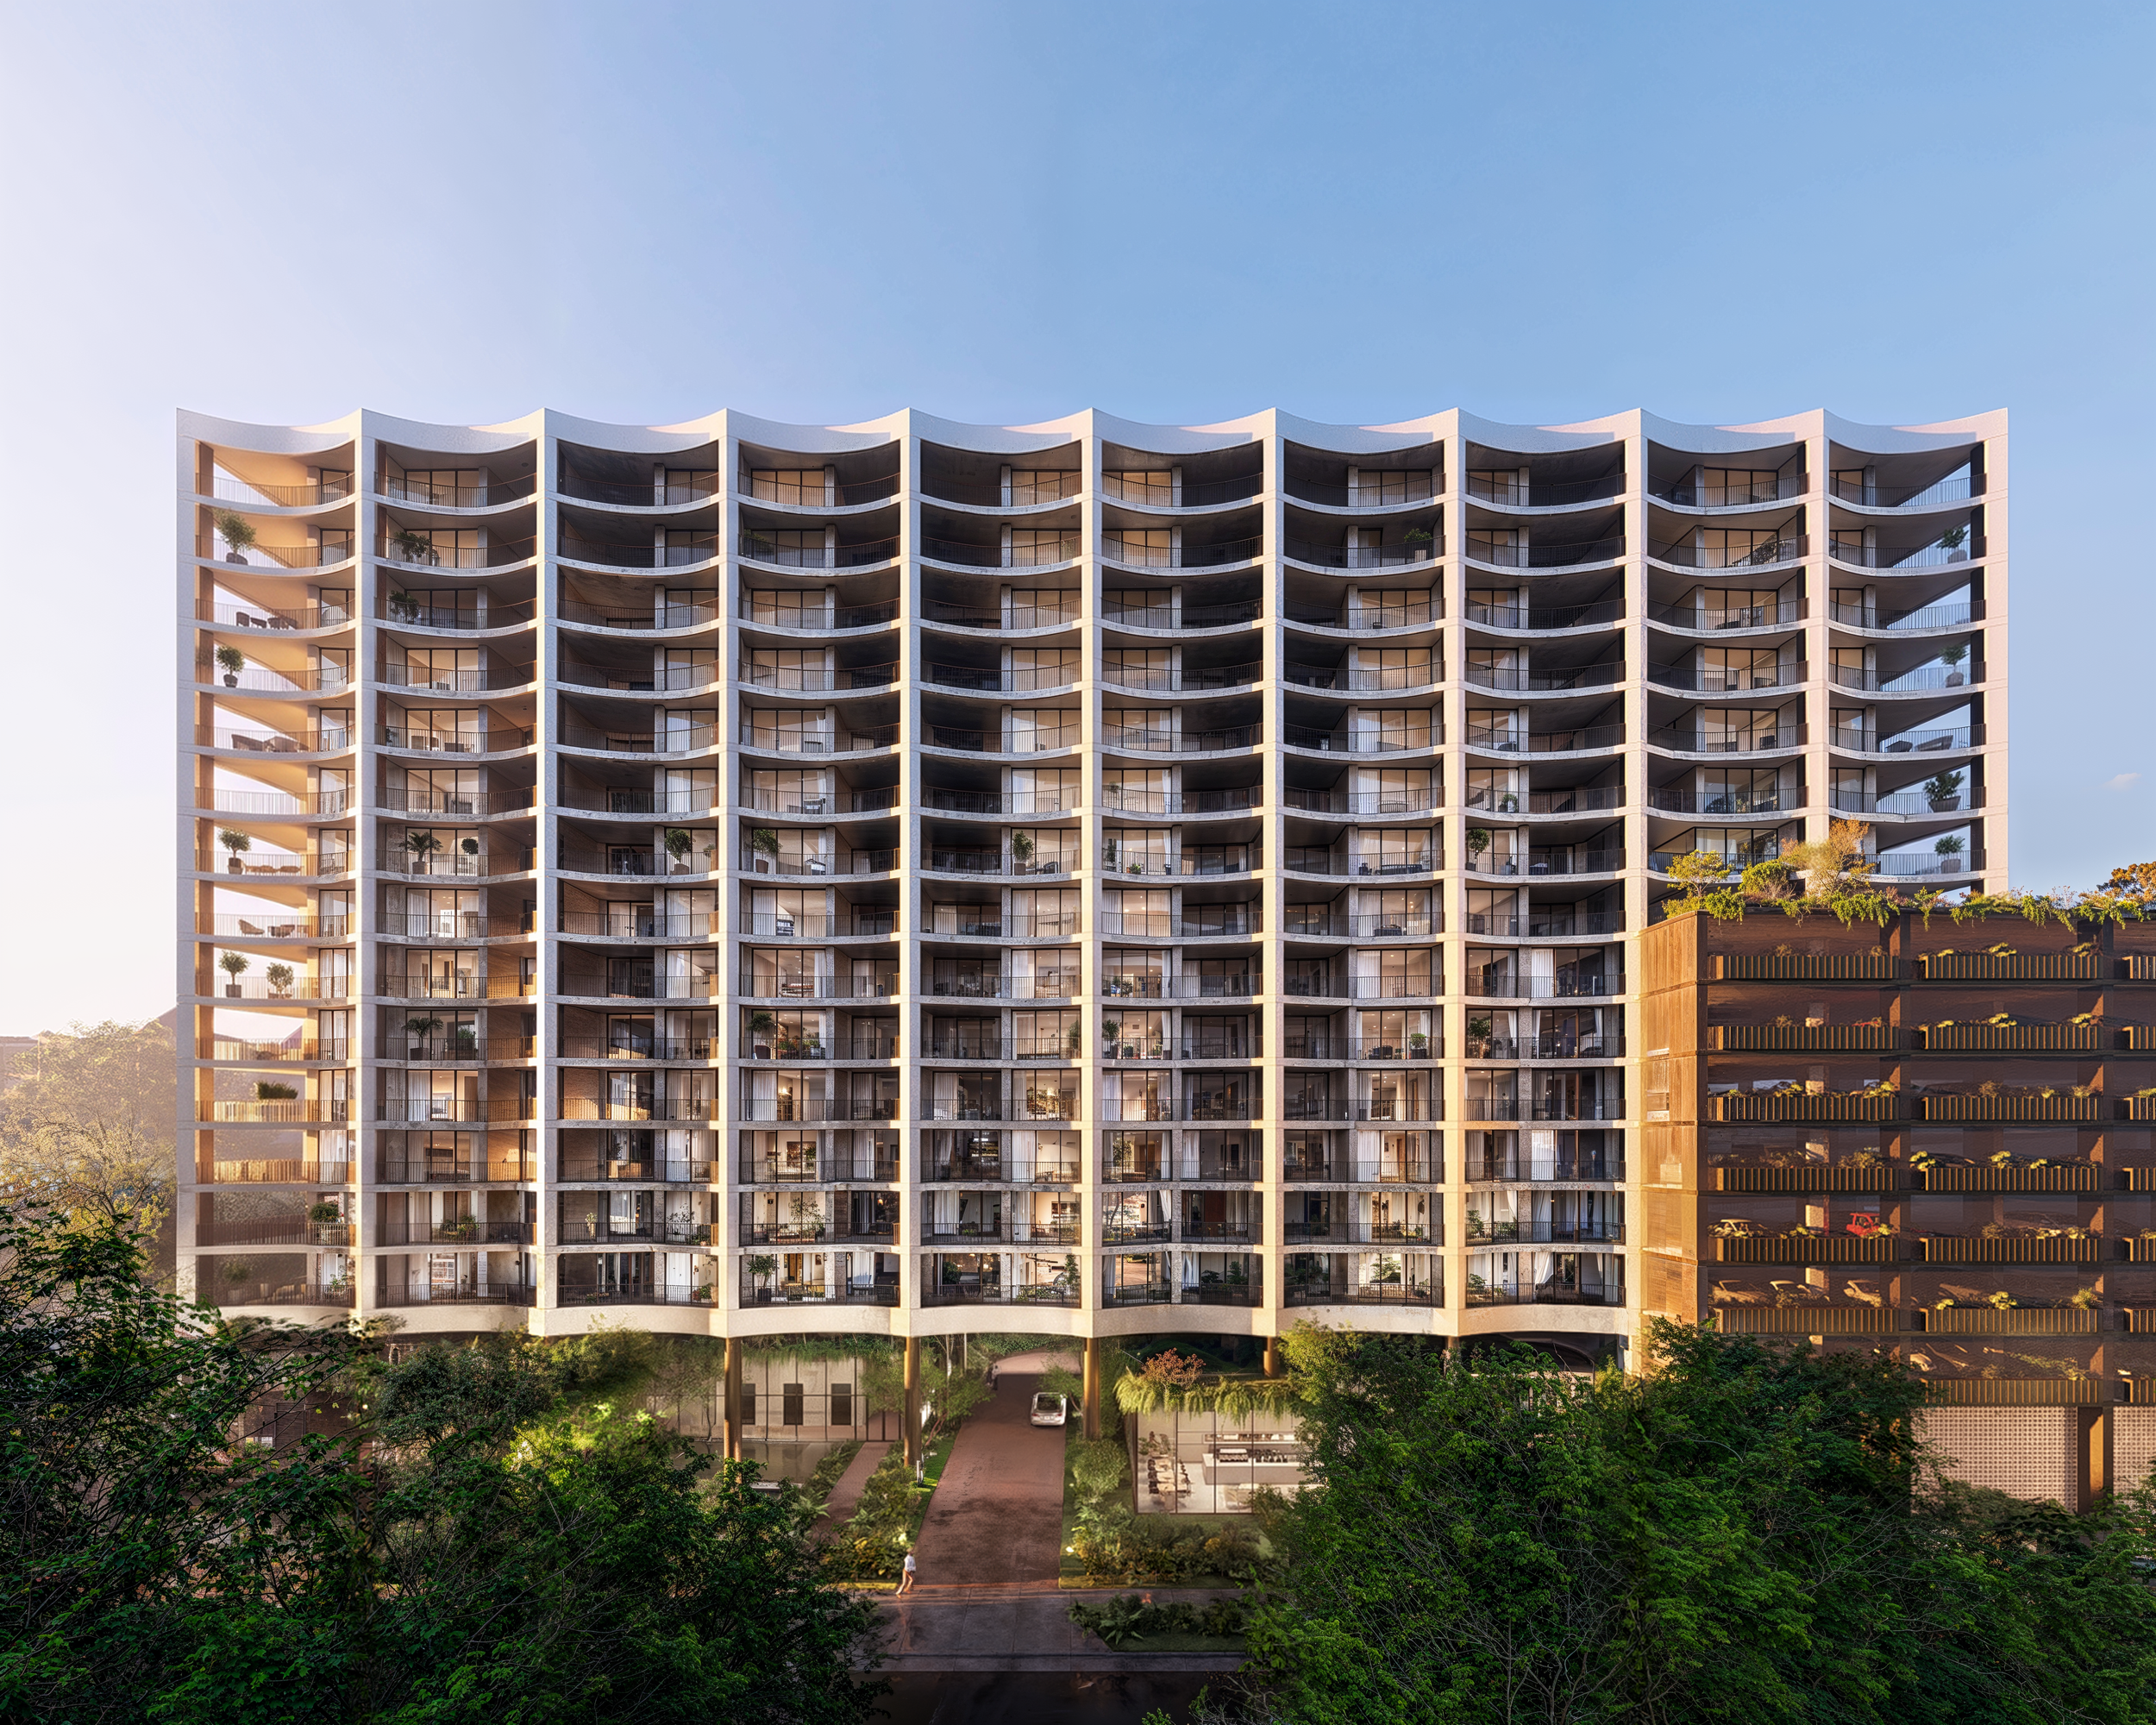
Mast Capital and BH Group have announced Raffles Residences Coconut Grove, the brand’s first standalone residential development, with 35 homes from $4.5 million and architecture by Brandon Haw.