
Meridiam Becomes Lead Investment Partner in Miami Beach Monorail Consortium’s Beach Corridor Plan
The Miami Beach Monorail Consortium has announced that the global infrastructure investment firm Meridiam has become the lead investment partner for the Consortium’s proposed mass transit monorail that would connect Downtown Miami and Miami Beach.
The Miami Beach Monorail Consortium has announced that the global infrastructure investment firm Meridiam has become the lead investment partner for the Consortium’s proposed mass transit monorail that would connect Downtown Miami and Miami Beach. The company, which has over $8 billion in assets under management across the globe, previously took over and completed the Port of Miami Tunnel project. The tunnel’s infrastructure required a workforce of 7,000 people, 83% of which came from the local community.
Over the past 30 years, studies have shown that the Interstate 395/MacArthur Causeway Beach Corridor is in need of a robust mass-transit solution that can benefit both visitors and regular commuters. The Miami Beach Monorail Consortium hopes to fulfill this public transit need for commuters and visitors alike with the County’s Strategic Miami Area Rapid Transit (SMART) Beach Corridor plan. The Corridor, which runs from the Design District and Downtown Miami to the Miami Beach Convention Center area, has been identified as one of the six SMART Plan Corridors by Miami-Dade County’s Transportation Planning Organization (TPO), which are priority areas that need public mass transit.
The Consortium presents the monorail as an innovative and modern model that will enhance Miami-Dade County’s standing as a smart city and alleviate traffic congestion on the MacArthur Causeway. The monorail is expected to create more efficient methods of transportation for Miami residents, while also generating thousands of jobs for its construction.
A Parsons study commissioned by Miami-Dade County estimates ridership for the monorail at more than 9,000 passengers per day and suggested elevated rubber tire technology as the best option to use for the Beach Corridor plan. These findings were later approved by Miami-Dade County’s TPO in December 2019.
“We are excited with the possibility of delivering another cutting-edge infrastructure project in Miami that will serve the community for decades to come,” said Jamie Rubin, CEO of Meridiam Infrastructure North America Corp. Meridiam is a founding member of the United Nations Sustainable Development Investment Partnership. “We have submitted a proposal that we hope meets all Miami-Dade County’s requirements to bring a much-needed public transit solution that will connect two of Miami’s most important hubs for residents, tourists and businesses. After the Port of Miami, it will be another sustainable and impactful infrastructure for Miami, dedicated to improving the quality of people’s lives”
“The success of the Port of Miami Tunnel would not have been possible without a strong partnership with hundreds of Miami companies with local knowledge,” said Christopher Hodgkins, Chief Executive Officer for Port of Miami Tunnel. “Meridiam can now utilize the expertise gained through the Tunnel project to once again hire local workers and companies who will help deliver the monorail safely and efficiently.”
Meridiam joins existing Consortium partners Genting and Aqualand Development, which submitted an unsolicited proposal in 2019 that became the source for a public Request for Proposals (RFP) that is currently being conducted by the County. The Consortium has submitted a proposal with further details on its approach in response to that RFP.
By Isabella Zimmermann
WeWork Lawsuit-Threat By Tenants Requesting Rent Relief Sends Shudders Through $5.5 Billion Of CMBS Debt
A group of WeWork’s members have moved toward suing the co-working giant in a letter sent by Walden Macht & Haran demanding that WeWork cease collecting rental fees. Many tenants have already requested rent relief, cancellation of their leases or stopped paying, which has put over $5.5 billion of CMBS loans backed by WeWork occupied properties at risk,
A group of WeWork’s members have moved toward suing the co-working giant in a letter sent by Walden Macht & Haran demanding that WeWork cease collecting rental fees. Many tenants have already requested rent relief, cancellation of their leases or stopped paying, which has put over $5.5 billion of CMBS loans backed by WeWork occupied properties at risk. Some of the CMBS loans back WeWork flagship locations in New York and San Francisco. WeWork, who was previously valued at $47 billion before dropping to a pre-covid valuation of $8 billion, has been working to renegotiate leases and has even skipped out to rent at some of their properties. This has in turn caused the price of bonds backed by payments from WeWork to fall drastically.
WeWork has made an effort to keep their locations open during the COVID-19 pandemic, but many of their tenants have expressed that they think WeWork should have shut their locations. Should WeWork not, Jim Walden of Walden Macht & Haran, threatened to start an arbitration process for WeWork members if the company continues to collect the fees in his letter to the company.
“State and local authorities around the country have directed businesses to cease operation and have prohibited workers, including our clients, from using their workplaces,” said Jim Walden. “As long as this pandemic prohibits our clients from using their WeWork office spaces, the purpose of their membership agreements is frustrated, thus excusing their obligation to pay membership fees.”
Tenants have accused WeWork of turning their backs on small business by continuing to collect fees. Due to WeWork’s short term lease model, the co-working giant is more at risk than the standard office landlord as many of WeWork’s tenants have elected not to renew and can be more flexible about actually going to an office as opposed to working from home. Many of WeWork’s tenants do not want to take the risk of going to their WeWork office location during the middle of the COVID-19 pandemic with 1.37 million confirmed cases in the US. Walden claims that the way the leases are structured are closer to that of gym memberships as opposed to true office leases, meaning that under New York law members are not liable for payments if they cannot physically access the space.
“Our clients have no legal obligation to pay their membership fees while the purpose of their membership agreements remains frustrated by the COVD-19 pandemic,” Walden wrote. “Ignoring this fact, WeWork continues charging these members full monthly fees and refuses to offer concessions or compromise.”
WeWork’s problems do not end there. Former CEO and co-founder Adam Neumann is reportedly under investigation for self-dealing by the New York State Attorney General. Additionally, one of WeWork’s major financial backers, the Tokyo-based SoftBank led by Masayoshi Son, walked away from a $3 billion tender offer in April 2020 which was part of the $9.5 billion bailout package SoftBank signed with WeWork in October 2019 following WeWork’s failed IPO. In May 2020 a special committee of WeWork board members filed a motion in Delaware to prevent SoftBank from disbanding the company as they purse legal action against the majority owner SoftBank Group Corp. WeWork’s special committee also represents minority shareholders including co-founder Adam Neumann. SoftBank and the SoftBank Vision Fund, which is a tech-focused venture capital fund with includes capital from the Saudi Arabian and Abu Dhabi sovereign wealth funds, Apple, Qualcomm, Foxconn and Sharp, have invested $14.25 billion into WeWork.
57 Ocean Condo Secures $58.5 Million Construction Loan from Bank OZK
Miami Beach’s 57 Ocean, a luxury seaside condominium located on Millionaire’s Row and developed by Multiplan Real Estate Asset Management, has announced that it has obtained a $58.5 million construction loan from Bank OZK, arranged by JLL Capital Markets.
Miami Beach’s 57 Ocean, a luxury seaside condominium located on Millionaire’s Row and developed by Multiplan Real Estate Asset Management, has announced that it has obtained a $58.5 million construction loan from Bank OZK, arranged by JLL Capital Markets. The financing will support the finalization of the 18-story project, which is already 50% complete and has reached the 11th floor this week. The 70-unit building is scheduled for completion in September of 2021.
MultiplanREAM, founded by Brazilian developer Dr. José Isaac Peres, has invested approximately $150 million in cash into the project and has ensured that each benchmark has been efficiently met despite the current COVID-19 pandemic. MultiplanREAM and 57 Ocean’s exclusive residential brokerage, Fortune Development sales, have reported that in just 45 days, 11 units totaling $46 million have gone under contract (an average of 1.3 sales per week), and attribute the project’s success on its location, contemporary designs, and robust assemblage of amenities and services.
“57 Ocean is not only delivering a unique, healthful-living lifestyle for buyers but also providing another reassurance for their real estate investment,” said Marcelo Kingston, Managing Partner of MultiplanREAM. “We are extremely proud to work with Bank OZK, the nation’s preeminent construction lender of marquee properties. We have confirmed that we will top out this August and deliver the building in September 2021, as we had originally promoted.”
The JLL Capital Markets debt placement team representing MultiplanREAM included Executive Managing Director Manny de Zárraga and Director Jesse Wright. The lending process began during the last week of March and lasted for 30 days, unlike the typical 90 that it normally takes.
“We are delighted to be working with MultiplanREAM in supporting the capitalization of this outstanding product,” said de Zárraga. “This liquidity will enable the developer to pursue new opportunities that may emerge during moments of the current global crisis while expanding its footprint in the State of Florida.”
Designed by Bernardo Fort-Brescia of ARQUITECTONICA, with interiors by Brazilian designer, Patricia Anastassiadis of Anastassiadis Arquitetos, 57 Ocean will offer two to four-bedroom residences starting at $1.5 million, with sizes ranging from 1,200 to upwards of 3,600 square feet. Of 57 Ocean’s 70 units—which more than half of have been sold—10 Sky Residences start at $6.5 million, while its full-floor penthouse is priced at $35 million. Units will feature expansive terraces that stretch up to 12 feet deep, as well as contemporary Italian kitchens and baths by Poliform. To date, more than half of the units have sold to buyers from high-income tax states, including New York and California, as well as high-net-worth individuals from Latin America.
57 Ocean offers amenities such as a holistic spa with treatments by One Ocean Beauty, a wellness pavilion with a thermal suite and a relaxation and mediation area, as well as poolside treatment with cabanas, a state-of-the-art fitness center with top-of-the-line Mylsle training equipment by MyEquilibria, and an indoor Technogym fitness center. In addition to this, there will be a children’s activity room, 24-hour concierge services, pool and beachfront concessions and attendants, and direct access to the nearby Miami Beach Walk.
“The excitement surrounding this development continues to build among ultra-luxury homebuyers worldwide—a testament to MultiplanREAM’s tremendous vision and subsequent success,” said Edgardo Defortuna, CEO of Fortune Development Sales. “We are now looking forward to the next big milestone—57 Ocean’s topping off later this summer.”
By Isabella Zimmermann | Images via DBOX
For more information about 57 Ocean, private showings or purchasing/ leasing information please fill out the form below:
Artefacto Begins Construction on New DOMO-Designed U.S. Flagship In Coral Gables
Brazilian furnishings brand Artefacto has celebrated the groundbreaking of their new US flagship in Coral Gables located on the high traffic US1. The 45,000 SF bi-level structure will feature an eye-catching modernist design by the renowned DOMO Architecture + Design, with interiors by Patricia Anastassiadis.
Brazilian furnishings brand Artefacto has celebrated the groundbreaking of their new US flagship in Coral Gables located on the highly-trafficked US-1. The 45,000 SF bi-level structure will feature an eye-catching modernist design by the renowned DOMO Architecture + Design, with interiors by Patricia Anastassiadis. The showroom is set to open mid-2021, and marks the brand’s 28th location worldwide.
Headed by CEO Paulo Bacchi, Artefacto entered the U.S. in 2002 as an anchor tenant to Coral Gables’ Merrick Park. Bacchi continues to make his mark on Coral Gables with the sleek new showroom at 101 South Dixie Highway, along one of Miami’s major transportation arteries.
“I’m very proud of our continued growth in Miami, and our showroom expresses the remarkable warmth and luxuries found in Artefacto home environments,” says Bacchi. “Now we will capture eyes in all directions with an innovative aesthetic that anchors US1 with incredible style.”
Exteriors will showcase dramatic street-level window displays of Artefacto’s exclusive collaborations with such notable talents as Alejandro Estrada, Piegatto, Sergio Matos and Patricia Anatassiadis. In-line with the brand’s commitment to embracing sustainable practices, the showroom’s exterior concept features lush, green walls with the highest level of quality natural, raw materials.
Lennar Locks Down $44.8 Million Construction Loan For Wynwood Green
Lennar has locked down a $44.8 million construction loan for Wynwood Green, an 11-story, 189-unit residential rental apartment building which will also feature 17,000 SF of commercial space and 324 parking spaces. The loan was provided by Santander Bank.
Lennar has locked down a $44.8 million construction loan for Wynwood Green, an 11-story, 189-unit residential rental apartment building which will also feature 17,000 SF of commercial space and 324 parking spaces. The loan was provided by Santander Bank. Wynwood Green will be located on a 1.26 acre site which was the former site of the popular food-truck and bar station at Wynwood Yard, 48, 56, 64, 70, 82, 90 and 98 NW 29th St. and 63 NW 28th street. Initial designs are by architecture firm Dorsky + Yue International. The site of Wynwood Green was sold to Lennar by David Lombardi of Lombardi Properties, who was one of the pioneers in the emergence of Wynwood.
The Miami-based publicly traded Lennar Corporation (LEN) is known as one of the largest homebuilders in the United States, but also retains ownership interests in 53 apartment communities. Wynwood Green would also be their first multifamily project within the city of Miami. Lennar Corporation is run by Executive Chairman Stuart Miller, whose father Leonard Miller was one of the founders in 1956. In 2019 Lennar was ranked 154th on the Fortune 500 and the company operates in 21 states.
Why Rent Strikes Are Bad for Everyone and What’s Going to be Done about Unemployment?
Since thousands of businesses were deemed non-essential and forced to shut their doors, reemployment assistance claims over the last six weeks have surpassed two million in South Florida. With a tourism-dependent economy plus an older population, Florida is more vulnerable to economic shock, which is why it is one of the top five states with the highest number of claims.
Since thousands of businesses were deemed non-essential and forced to shut their doors, reemployment assistance claims over the last six weeks have surpassed two million in South Florida. With a tourism-dependent economy plus an older population, Florida is more vulnerable to economic shock, which is why it is one of the top five states with the highest number of claims. The longer the standstill goes on, the worse the economic fallout will be.
As May rents come due and unemployment rates continue to jump, providing assistance to households should be a top priority for policymakers. The prospect of a rent strike has been trending in the news and on social media, but a voluntary movement to skip rent payments could destabilize not only the housing market, but the American economy as well. How many months of working capital do small businesses have to stay afloat, in order for those furloughed and laid off employees to have jobs to return to after nationwide and state stay-at-home orders are eased and how will South Florida’s real estate market fare in the coming months?
May Day: May 1st Is Here
Multifamily landlords were pleasantly surprised with April collections. In an exclusive webinar interview hosted by PROFILE last week, President of Tate Capital, James Tate, who has over $1B assets under management, told us “We’re 90% collected,” talking about his 10,000+ door multifamily portfolio. Now it’s May 1st and everyone is wondering what May rent collections will be. “May 1st will be a good deciding point to see how many people default,” added Allen Morris, Chairman and CEO of the Allen Morris Companies.
Morris said his April multifamily rent collections were at 95%. He’s opening two new apartment buildings in Orlando this summer and is taking a proactive leasing approach. “People are signing leases, assuming the University of Central Florida is holding its fall semester. We’re giving tenants a guarantee in their lease. If they delay opening the university, we will delay rent until school opens.” Offering tenants flexibility gives them the security to sign leases now and is helping to forge a positive landlord-tenant relationship that will be dependent on open communication, should issues with payment arise in the future.
Trending: Socialist Whispers
With talks of rent strikes sweeping the country, landlords have been portrayed as vultures preying on the pockets of financially insecure tenants, when they remain responsible for property taxes and other carrying costs that help pay for public improvements, education and other municipality benefits. Diligent landlords are communicating with their tenants and weeding out those who are taking advantage of the public health crisis, says Shahab Karmely, CEO of KAR Properties. Those who can, should pay rent to support the services their communities need. Those directing their frustrations toward landlords may have valid concerns: with the economy shut down by government-mandated order, how are people supposed to pay bills and keep businesses running?
In New York, politicians pushing socialist rhetoric and big government reach such as Alexandria Ocasio Cortez have called for rent strikes and rent cancellations. Movements in New York City even claim to have “identified” landlords who can take a “shave”. Lack of payment means that owners will not be able to stay in business and manage the building to the tenant’s expectations, including paying for things like common area maintenance (think: how much does it cost for a cleaning crew to wipe down all public surfaces in a building multiple times a day). Landlords also pay property tax, insurance, debt service, management fees and capital expenditures for improvements.
Most commercial real estate investments are made by an owner contributing an equity portion to a project, but a majority of the total costs are funded through debt that is usually collateralized by the asset (if it’s senior debt). Typical sources of debt include pension and life insurance funds, which could be the life savings of either a tenant or a landlord. When landlords are unable to meet their debt obligations, the cascading effects don’t stop at their coffers, but trickle down to all Americans. Not making rent payments could derail future opportunities for many, including someone’s retirement age.
Karmely added “The real pandemic to hit New York City multifamily was the legislature that strangled the landlords in this business,” which will continue to make Florida’s real estate investment climate more attractive. Multifamily product in New York City has been trading between 3-5% cap rate, depending on the neighborhood. The low trading cap rates for core product has made some investors nervous about paying such a premium for an asset that the New York government has so much control over.
Another risk for New York investors is that South Florida’s pricing for comparative rental and condo inventory is cheaper than it’s NYC counterpart, while providing higher quality-of-life with more space and building amenities. From an investment perspective, it is also easier to manage assets in Florida where there is no government-enforced rent control, rent stabilization, or near-impossible eviction procedures for delinquent tenants.
Opportunities on the Horizon
The cure to the virus is causing an economic calamity that is hitting everybody and everything, which means opportunities will be on the horizon three to four months from now when property owners' cash reserves run dry, especially for retail and restaurant real estate assets.
Many have posited, is the cure worse than the virus? How long can residential and commercial tenants pay their rent amid an economic shutdown? Will we be able to produce our way out of a recession with unemployment in the double digits? Likely not - Uncle Sam will be waiting in the shadows with hand outstretched to collect his dues. As we all sit on the sidelines, awaiting our fates, the solution appears to be a function of time.
“My biggest concern is that we were hit with an 11 magnitude earthquake, and we all got knocked down. Unfortunately, after a major earthquake in coastal areas there is a tsunami. My concern is how are these small businesses supposed to remain open and sustain themselves for the next six to eight months unless something material is done by the federal government? Who’s going to hire those 30 million unemployed people back? If you ask me why I can’t sleep at night, that’s what I’m really concerned about,” opined Tate to cheers of “Jimmy Tate for President!”
-- Special reporting by the PROFILEmiami Team. Isabella Zimmermann, Katya Demina and Demetri Demascus contributed to this article.
Miami City Commission Approves $6.9 Million To COVID-19 Rent & Utility Assistance For Low-Income Households
The Miami City Commission voted unanimously to approve $6.9 million in rent and utility assistance for low-income residents who recently lost their jobs due to the COVID-19 pandemic. Independent contractors such as realtors are not eligible for the loans, neither are those receiving rental subsidies or are behind on their payments.
The Miami City Commission voted unanimously to approve $6.9 million in rent and utility assistance for low-income residents who recently lost their jobs due to the COVID-19 pandemic. Independent contractors such as realtors are not eligible for the loans, neither are those receiving rental subsidies or are behind on their payments. Those eligible for the payments are one-person households earning less than $38,400 per year, two-person households earning less than $43,920 per year, three-person households earning less than $49,380 per year, and four-person households earning less than $54,840 per year. The $6.9 million which was approved also includes $2 million in federal and state grand money for households which earn less than 60% of the Miami-Dade County median income. Each eligible household will be limited to receive a maximum of $1,500 and applicants must show proof that they have los their jobs after March 1 and have paid rent through February 2020. The payments will be sent directly to landlords and utility companies. The funds will only be available until enough applications have been received to deplete the available funding and the application period ends at 5 P.M. on May 8.
Miami has been in an affordable housing crisis due to rapidly rising rents and property values. 35.4% of city residents reportedly spend more than 50% of their household income on their housing. On April 2 Florida Governor Ron DeSantis issued an executive order which barred evictions and foreclosures for 45 days, but it is expected that there will be mass eviction cases filed due to unpaid rent when the order expires.
Gianluca Vacchi, Italian Millionaire Turned Instagram Sensation, Lists Sunset Harbour Penthouse In Miami Beach
Instagram dance celebrity Gianluca Vacchi has listed his Sunset Harbour penthouse in Miami Beach. From a successful multimillion dollar packaging and machinery company to an Instagram sensation with over 14 million followers going by the title of being a “Pop Artist of a Global Lifestyle.”
Instagram dance celebrity Gianluca Vacchi has listed his Sunset Harbour penthouse in Miami Beach. From a successful multimillion dollar packaging and machinery company to an Instagram sensation with over 14 million followers going by the title of being a “Pop Artist of a Global Lifestyle,” Gianluca Vacchi has been named everything from “the most interesting man in the world,” “The Dos Equis guy” has been seen frolicking with some of the biggest celebrities and DJs in the world and staring on J Balvin’s music video showcasing his astonishing dance moves. Gianluca Vacchi has decided to list his Miami Beach eclectic penthouse for $10,900,000 with Dina Goldentayer of Douglas Elliman.
With a new found love for his life in Miami Beach, Vacchi has decided to move on and purchase a single family home with plans to spend a lot more time in Miami. All of his properties are personally designed by him and specifically with his Miami Beach penthouse he poured his passion into creating a sanctuary in the heart of Miami Beach’s Sunset Harbour. Calling his home S2S “Sunrise to Sunset” towering at 26 stories, interiors over 7,000 SF, 4 bedrooms + staff, 3 parking, 2 views and 111 linear feet on the Biscayne Bay, his completely reconstructed and renovated mansion in the sky showcases a minimalist and modern aesthetic.
Located at 1800 Sunset Harbour #TS2, upon arrival into the 2500 SF living salon there is a DJ booth where Vacchi spends much of his time entertaining and showcasing his professional dance moves. The expansive unit features a dramatic master suite with terrace facing the ocean, a private chef’s kitchen filled with sunlight, an open concept media room, and endless natural light from dual East/West exposures. Plus, a spectacular VIP master suite with fireplace and an office floating over the bay. The residence offers breathtaking views of the Downtown skyline from a private 1600 SF rooftop and is just steps away from the vast array of shops, fitness studios, spas, cafes and the top restaurants in Miami Beach’s Sunset Harbour neighborhood.
In his early teens, Vacchi was a professional skier, fast forward to when he began his business career in Italy by taking over his family’s business, IMA Group world leader in the design and manufacture of automatic machines for the processing and packaging of pharmaceuticals, cosmetics, food, tea and coffee. Today, IMA’s market cap is $3B euros and has been named as the 5th most top performing family owned company of the world. Vacchi also ventured into creating his first startup which was the plastic watches called “Toy Watch.” After deciding to take a back seat while still being involved in the packaging company, Vacchi began doing what made him happy which was experiencing the world, dancing to music and DJing now with the liking of over 14 million instagram followers Vacchi has become an international sensation and is hired to Dj all over the world at some of the biggest nightclubs.
For more information about purchasing and scheduling a showing for 1800 Sunset Harbour #TS2 please fill out the form below:

Rewind: W. Allen Morris, Shahab Karmely And Jimmy Tate On Emerging From the COVID-19 Crisis
On April 30, 2020 PROFILEmiami hosted an interactive webinar discussion focusing on emerging from the COVID-19 pandemic and the resulting economic fallout’s impact on the South Florida real estate market. The panel featured South Florida real estate titans W. Allen Morris, Shahab Karmely and Jimmy Tate.
On April 30, 2020 PROFILEmiami hosted an interactive webinar discussion focusing on emerging from the COVID-19 pandemic and the resulting economic fallout’s impact on the South Florida real estate market. The panel featured South Florida real estate titans W. Allen Morris, Shahab Karmely and Jimmy Tate who explored topics such as: what effects will we see on South Florida’s real estate markets, how are South Florida’s leading real estate professionals reacting to the crisis, how do you think the workspace landscape will look after we “get back to normal,” where will the smart investments be made and how are they preparing for future opportunities.
Speakers:
W. Allen Morris - Chairman, President & CEO, The Allen Morris Company
Shahab Karmely - CEO, KAR Properties
James D. Tate - President, Tate Capital
Moderator: Demetri Demascus - CEO & Co-Founder, PROFILEmiami
Watch:
Topics:
What is your personal outlook on how this will ultimately affect the South Florida real estate markets? Will there be permanent changes to the market or the industry?
How are you handling projects currently under construction? What lessons did you learn from past recessions and how did they shape how you’re handling today’s crisis? Have you learned any lessons from the COVID-19 crisis?
If you have capital to deploy, what are principals telling their acquisitions teams right now?
Where do you think we will see opportunity open up? Who is overleveraged? When will we begin to see properties fall into distress?
Does a property need to fall into distress for COVID-19’s impact to create an opportunity? What non-distressed opportunities will we see?
Will opportunity open up for different ways to add value to existing properties or will it change the way you think about developing new properties?
Where and how will the smart investments be made?
Who is willing to give you term sheets right now and what type of lenders pulled their term sheets?
How are you preparing to get your offices back to work and how will the work landscape have changed when we get back to the “new normal.”
Partners:
WEBINAR SPONSORSHIP
Interested in sponsoring PROFILEmiami events? Generate exposure for your brand and connect directly with some of South Florida’s top real estate professionals. Contact us today to inquire about Sponsorship Opportunities.
PLEASE COMPLETE THE FORM BELOW
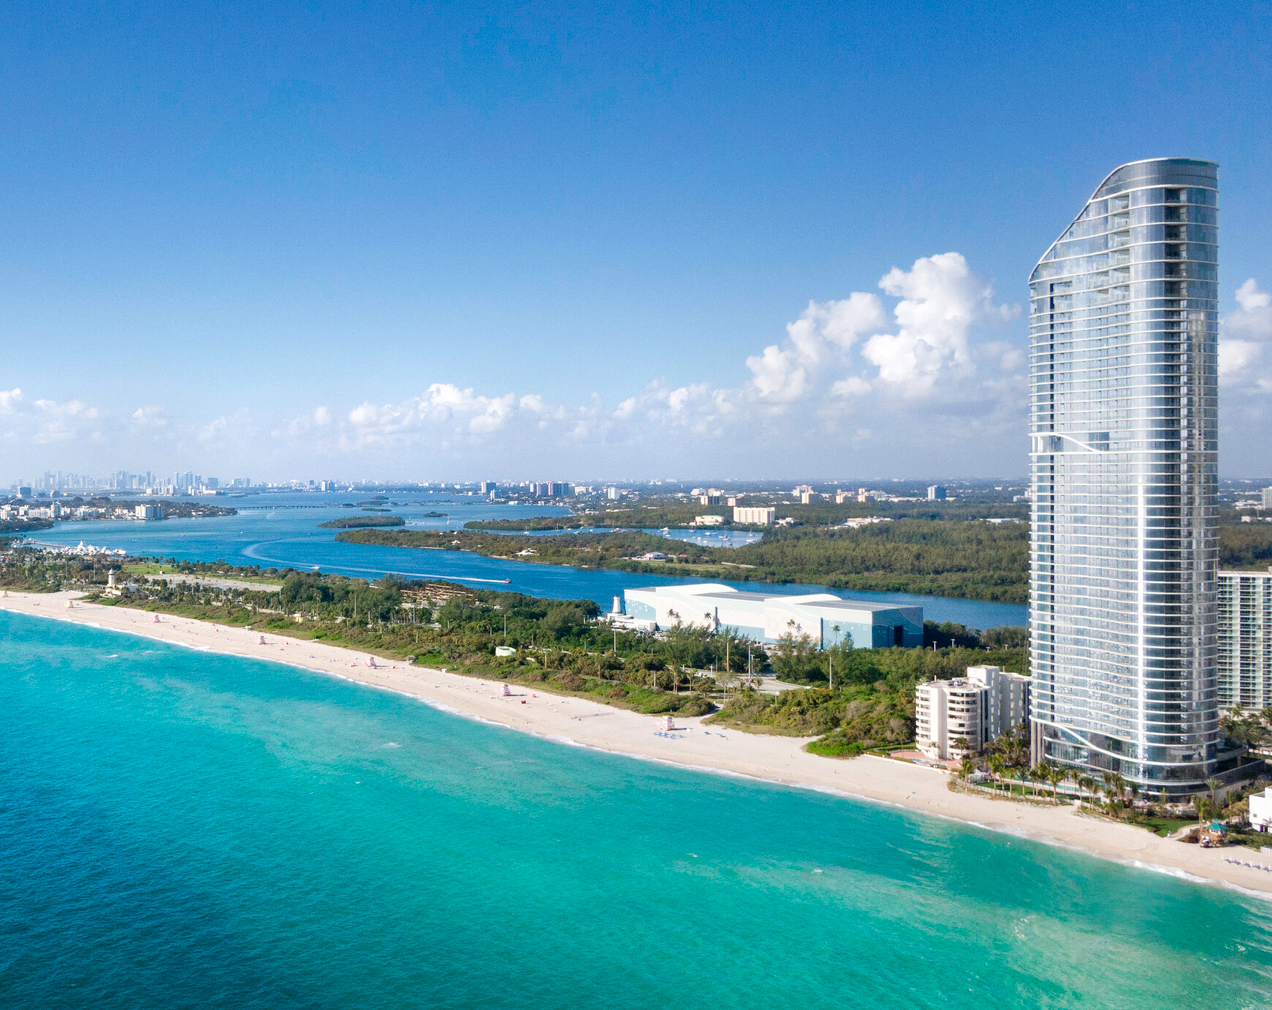
Developers of The Ritz-Carlton Residences Sunny Isles Beach Pay Off $212 Million Construction Loan
Fortune International Group and Château Group, joint developers of The Ritz-Carlton Residences, Sunny Isles Beach, have paid off a $212 million construction loan on the newly opened condominium tower. The developers received the loan from Bank OZK in September 2016.
Fortune International Group and Château Group, joint developers of The Ritz-Carlton Residences, Sunny Isles Beach, have paid off a $212 million construction loan on the newly opened condominium tower. The developers received the loan from Bank OZK in September 2016. The news comes on the heels of a string of triumphs for the property, which is managed by The Ritz-Carlton and is one of the brand’s only standalone oceanfront condominium high-rises worldwide. The 52-story building at 15701 Collins Avenue, which was designed by award-winning architect Bernardo Fort-Brescia of Arquitectonica and features interiors by acclaimed Florentine architect Michele Bönan, was completed on Feb. 24 when it received its temporary certificate of occupancy (TCO). The tower is already more than 80% sold. Since the building broke ground, each milestone associated with its rise has been monumental, including the pre-construction sell-out of all four penthouses, a record feat for the area. Now, in the midst of the COVID-19 pandemic, the developers have seamlessly completed 100 closings, with a great number of them conducted virtually. They have additionally finalized new sales totaling more than $30 million.
“Paying off this loan so quickly after opening the tower, and in the midst of these extremely challenging times, further confirms the support for our project and the excitement it has generated among buyers across the globe,” said Manuel Grosskopf, CEO of Château Group.
“Our residents have been praising the end-result of the thoughtful and detailed work that has gone into creating and delivering this dream of ours,” said Edgardo Defortuna, President and CEO of Fortune International Group. “The project’s longstanding sales success, as well as these most recent triumphs, have been a testament to the buyers’ recognition of a high-quality project paired with a high-level of service.”
“The most high-profile buyers in the world have been purchasing homes in this condominium, knowing that the services by The Ritz-Carlton, amenities, architecture, and designs will exceed every expectation,” added Grosskopf.
“The Ritz-Carlton Residences, Sunny Isles Beach are a new crown jewel for Miami’s ultra-luxury oceanfront property market,” continued Defortuna.
The Residences, which have no hotel on the premises, resides on a prime coastal location with 250’ of beachfront. The tower is comprised of 209 residences with a private club level on the 33rd floor including private suites for resident guests, beach restaurant and bar, two pool decks, a kids club, full-service spa, fitness center and wellness center, among other top-line amenities. Each of the homes, all of which are smart-technology-ready, include private entrances, both living and master bedrooms with direct oceanfront views, walk-in closets, and pre-wiring for high-speed internet access and Wi-Fi. Remaining residences start at $2.6 million and sales are overseen by Fortune International.
For more information about The Ritz Carlton Residences, Sunny Isles Beach, private showings or purchasing/ leasing information please fill out the form below:


A newly completed seven-bedroom waterfront estate at 1155 Belle Meade Island Drive is coming to market with an announced asking price of $43.9 million.