
Miami-Dade County And Related Urban Development Group Break Ground on Three Round Towers
Miami-Dade County Mayor Carlos A. Gimenez, Chairwoman Audrey M. Edmonson and Related Urban Development Group (RUDG) have celebrated the ground-breaking of Three Round Towers B&C and Brisas del Este, an affordable housing development encompassing three buildings for a combined total of 383 units in the Allapattah area of Miami-Dade County.
Miami-Dade County Mayor Carlos A. Gimenez, Chairwoman Audrey M. Edmonson and Related Urban Development Group (RUDG) have celebrated the ground-breaking of Three Round Towers B&C and Brisas del Este, an affordable housing development encompassing three buildings for a combined total of 383 units in the Allapattah area of Miami-Dade County. They were joined by a special guest on this occasion, the Honorable Dr. Benjamin S. Carson, Secretary for the U.S. Department of Housing and Urban Development.
The Three Round Towers development was originally built in 1970 on approximately 6.98 acres and included three towers (Towers A, B and C), a Community Center and parking for residents. Tower A was substantially renovated in 2018 by Related Urban. The current renovations are focused on the major rehabilitation of Towers B and C along with the construction of Brisas del Este, a new 120-unit affordable housing project. RUDG, the affordable housing arm of prolific developer Related Group, will serve as Miami-Dade County’s developer partner.
The rehabilitation of the two existing towers and the new construction of Brisas Del Este will result in stylish, well-appointed residences tailor made to serve a primarily senior population through elevated accessibility options. The projects will serve residents from 30% area median income (AMI) up to 80% AMI and will be completed in the beginning of 2022.
“By fully leveraging multiple financing sources, our County is paving the way more for smart projects that create vital affordable housing for our residents,” said Miami-Dade County Mayor Carlos A. Gimenez. “Miami-Dade’s public-private partnership with Related Urban Development Group has been a key component leading to the success of this particular project, and I look forward to the County’s continuing wise use of P3’s moving forward.”
The total development cost for the three buildings is more than $106 million. The layering of financing makes this development the largest of its kind in the nation utilizing Opportunity Zone Funds ($24 million) in combination with other federal and HUD resources, such as Low-Income Housing Tax Credits (LIHTC), Rental Assistance Demonstration funding (RAD), Home Investment Partnerships (HOME) from the City of Miami, and a Purchase Money Mortgage (PMM) of $18 million from Miami-Dade County to the developer. County and State surtax funds are also being invested in the project. More importantly, the Opportunity Zone investment of $24 million was made by personally by Related Group CEO Jorge M. Peréz.
“The redevelopment of Three Round Towers and the addition of Brisas Del Este leverages the widest range of financing available in affordable housing development,” said Albert Milo, Jr President of RUDG. “It is truly a first-of-its-kind project made possible by our partners at the County, who we have worked with over a dozen times to create transformative affordable housing solutions across Miami-Dade. Through collaborations like this, we are able to continue making a real difference for the residents of the communities we build in.”
“With this project we are proving that Opportunity Zone funding is scalable for major affordable housing developments,” said Michael Liu, Director for Miami-Dade Public Housing and Community Development (PHCD). Liu continued, “With a visionary like Jorge Perez and extraordinary builder in Albert Milo, our plan to transform all of our public housing with private sector partners will succeed.”
OFF-WHITE c/o VIRGIL ABLOH™ Opens Flagship Store In Miami Design District
OFF-WHITE c/o VIRGIL ABLOH™ has opened in Miami Design District (MDD). The new two-story flagship location is located at 127 NE 41st Street and will feature seasonal men's and women's collections of the luxury brand’s ready-to-wear streetwear.
OFF-WHITE c/o VIRGIL ABLOH™ has opened in Miami Design District (MDD). The new two-story flagship location is located at 127 NE 41st Street and will feature seasonal men's and women's collections of the luxury brand’s ready-to-wear streetwear. The Miami Design District store was designed by Virgil Abloh in collaboration with OMA’s Director of Architecture Samir Bantal to operate as a flagship retail store, fulfillment center, cafe and multipurpose event space that can host a runway fashion show or art show.
COVID-19 reportedly contributed to Abloh and Bantal’s decision to make the location flexible and cater to customers who are shopping online as opposed to in-store. In addition the walls are modular and can be compressed or opened up to change the space for different uses as well as opening up the front facade the outdoors. The store was designed with an industrial aesthetic with concrete floors, corrugated metal walls and mesh ceiling panels. Apparel will be displayed on stainless steel shelving with black marquina and white Carrara marble platforms, all of which, including the furniture, is modular and on wheels to be easily moved.
In addition to being the founder of OFF-WHITE c/o VIRGIL ABLOH™, which he founded in 2012, Abloh is also the artistic director of Louis Vuitton's menswear collection. OFF-WHITE c/o VIRGIL ABLOH™ goods are manufactured in Milan with a core value of the brand to be made from the best available and particular opinion regarding fabric, fit and fabrication.
Miami Design District was developed by Miami Design District Associates, led by Craig Robins, in a partnership between his firm Dacra and L Catterton Real Estate, a global real estate development and investment fund that was established in 2016 by Catterton, LVMH and Groupe Arnault. MDD is a creative neighborhood with shopping, dining, contemporary art, design and events. MDD is home to over 120 flagship stores like Balenciaga, Hermes, Rolex, Fendi, Panerai, Tag Heuer, Dior, Cartier, Louis Vuitton, Tesla, etc. MDD also offers three cultural and art institutions being ICA Miami, the de la Cruz Collection and Locust Projects.
Taurus Investment Holdings To Redevelop Civica Center Into Medical Space
The Boston-based Taurus Investment Holdings has acquired the Civica Center for $30.5 million in Miami’s hot Allapattah neighborhood. The Civica Center is located at 1050 NW 14th Street at the entrance to Miami’s Health District, which is home to a large concentration of medical firms and institutions including the University of Miami Leonard Miller School of Medicine.
The Boston-based Taurus Investment Holdings has acquired the Civica Center for $30.5 million in Miami’s hot Allapattah neighborhood. The Civica Center is located at 1050 NW 14th Street at the entrance to Miami’s Health District, which is home to a large concentration of medical firms and institutions including the University of Miami Leonard Miller School of Medicine. The Civica Center broke ground in 2014 and was developed by the Swerdlow Group. The two-story retail property was sold with an adjacent parking lot and the deal also included a small office building. The Dallas-based Rockpoint Group was the seller.
Tenants at Civica Center include 7-Eleven, Au Bon Pain, Burger King, Chicken Kitchen, Dunkin’ Donuts, Flavors, Food Court, Gateway Dental, Jimmy John’s, La Estancia, Optical Boutique, Panera Bread, Pasha’s, Quest Diagnostics, Salsa Fiesta, and Smoothie King, amongst others.
Taurus has been agressively acquiring life-sciences and medical buildings and plans to convert the 0.77-acre parking lot into a giant 460,000-square-foot medical office building. It also plans to expand the existing 47,000-square-foot retail building into a 62,500-square-foot retail and medical office property. Taurus expects to start work on the redevelopment in the next 24 months.
Billionaire Investor Carl Icahn Officially Relocates Icahn Enterprises From Manhattan To Sunny Isles Beach
Billionaire investor Carl Icahn has reportedly officially finalized the move of Icahn Enterprises from New York City to South Florida. Icahn Enterprises has moved into their 23,463 SF lease on the 12th floor and penthouse of Milton Tower in Sunny Isles Beach. The firm previously was located in the General Motors Building in Manhattan.
Billionaire investor Carl Icahn has reportedly officially finalized the move of Icahn Enterprises from New York City to South Florida. Icahn Enterprises has moved into their 23,463 SF lease on the 12th floor and penthouse of Milton Tower, located at 16690 Collins Ave. in Sunny Isles Beach. The firm previously was located in the General Motors Building in Manhattan. Icahn is the latest ultra high-net-worth investor to relocate his firm from high tax northern-states such as New York to more tax-advantageous states such as Florida.
Milton Tower was completed in March 2020 and was developed by J. Milton & Associates. The office tower spans 102,000 SF, rising 12-floors with 6-floors of parking. Office spaces are customizable and range from 3,000 square feet to 13,900 square feet and feature floor-to-ceiling glass windows offering views of the Atlantic Ocean, Intracoastal and Sunny Isles skyline. Milton Tower offers first-class amenities include 24/7 access and security, a gym, ground-floor cafe, wifi-connected common areas, electric vehicle charging, emergency power, outdoor terraces and parking.
Leasing was launched in 2019 and the building is currently 50% occupied with tenants including family offices, law firms, investment companies and hedge funds. Much like Icahn, there is reportedly strong interest from firms relocating from the Northeast.
The Estate Companies Acquires Former Ramada Hotel in Hialeah for $15.25 Million
The Estate Companies (EIG), a leading developer of luxury multi-family projects throughout South Florida, has announced the $15.25 million acquisition of a five-acre site occupied by a former Ramada Hotel at 1950 W. 49th St. in Hialeah. The closing took place August 7th with $11.5 million in financing arranged by LV Lending, a local private lender.
The Estate Companies (EIG), a leading developer of luxury multi-family projects throughout South Florida, has announced the $15.25 million acquisition of a five-acre site occupied by a former Ramada Hotel at 1950 W. 49th St. in Hialeah. The closing took place August 7th with $11.5 million in financing arranged by LV Lending, a local private lender. The loan was facilitated by Camilo Niño, Ricardo Uribe and Alen Hernandez of LV Lending on behalf of 1950 Hialeah Holdings, LLC, an entity of The Estate Companies (EIG).
The non-operational 258-room Ramada hotel was originally constructed in 1970 with expansions completed in 1973, 1979 and 1988. The site is located directly adjacent to the Palmetto Expressway and the 103rd Avenue exit, providing extremely high visibility and accessibility.
“We are thrilled with this acquisition as it presents a rare opportunity to own all the fundamentals we look for in an asset,” stated Jeffrey Ardizon, principal, The Estate Companies. “The site is situated on arguably the City of Hialeah’s busiest corridor and main artery. The City of Hialeah is a market with very high barriers to entry, strong demographic support and close in proximity to some of the largest employment hubs in South Florida. In addition, the area offers great walkability with a variety of social, dining and entertainment options, including the Westland Mall, just a short distance away.”
Ardizon added, “The distressed hotel sector has created investment opportunities that firms like ours are ready and able to capitalize on. Not all sites are created equal, and buyers need to be nimble and flexible in order to ensure repurposed assets meet the current market demands.”
“We take our hats off to Camilo Niño and his team at LV Lending who arranged our financing in such a short period of time,” Ardizon added. “They were seamless in their execution and a pleasure to work with on this transaction.”
License Agreement Ends Between Brightline And Virgin Trains USA Amid COVID-19 Pandemic
The partnership between Brightline and Virgin Trains has been terminated amid the COVID-19 pandemic and South Florida’s new commuter train service will go back to using the Brightline brand. The train service which runs between Downtown Miami, Fort Lauderdale and West Palm Beach, has not run since March 25 and has laid off 250 employees.
The partnership between Brightline and Virgin Trains has been terminated amid the COVID-19 pandemic and South Florida’s new commuter train service will go back to using the Brightline brand. The train service which runs between Downtown Miami, Fort Lauderdale and West Palm Beach, has not run since March 25 and has laid off 250 employees. Virgin Trains USA was expected to make a minority investment into the Brightline train system which was set to complete their rebrand to Virgin Trains by mid-2020. Brightline and Virgin Trains had signed a Licensing Agreement in November 2018 although Brightline’s parent company, Fortress Investment Group, reportedly sent a termination notice in July of this year.
WeWork Leaves Lincoln Road Location As Landlord Seeks $19.5 Million In Unpaid Rent
WeWork’s trouble’s due to COVID-19 continue as the landlord of their 350 Lincoln Road location has sued the co-working giant in Miami-Dade Circuit Court. SML 350 Lincoln Inc., an entity controlled by Shaul Levy and Meir Levy, alleges that WeWork breached their lease by failure to pay rent in April, May and June.
WeWork’s trouble’s due to COVID-19 continue as the landlord of their 350 Lincoln Road location has sued the co-working giant in Miami-Dade Circuit Court. SML 350 Lincoln Inc., an entity controlled by Shaul Levy and Meir Levy, alleges that WeWork breached their lease by failure to pay rent in April, May and June while occupying the 40,000 square foot space and now owes in-excess of $19.5 million in back-rent and legal fees. WeWork said in a statement that the lawsuit is without merit and will continue to work with the landlord to resolve the situation in a mutually beneficial fashion. WeWork’s 16-year lease at 350 Lincoln Road began in November 2014 and runs through October 2030.
WeWork will close the Lincoln Road location on August 14 and has also moved to consolidate its Miami Beach members to 429 Lenox Avenue. Last month we reported that Goddard Investment Group has moved to evict WeWork from the Lenox Avenue location, but the two parties were reportedly able to resolve their differences.
WeWork, which is now led by CEO Sandeep Mathrani, still has locations in Downtown Miami, Brickell and Coral Gables. Times have not been good to WeWork following its failed IPO in 2019. The coworking giant recently announced that it will being closing its first location to ever open in New York City and saw its valuation slashed from over $47 billion to $2.9 billion.
In May 2020, a group of WeWork’s members moved toward suing the co-working giant demanding that WeWork cease collecting rental fees. Many tenants had already requested rent relief, cancelled their leases or stopped paying, which put over $5.5 billion of CMBS loans backed by WeWork occupied properties at risk. Some of the CMBS loans back WeWork flagship locations in New York and San Francisco. WeWork has retained Newmark Knight Frank and JLL to try to renegotiate leases and negotiate concessions from landlords at some of their properties as the firm try to stave off a potential bankruptcy.
WeWork’s problems do not end there. Former CEO and co-founder Adam Neumann is reportedly under investigation for self-dealing by the New York State Attorney General. In addition, the Tokyo-based SoftBank led by Masayoshi Son and a special committee of WeWork board members have been locked in a legal battle after Softbank walked away from a $3 billion tender offer in April 2020 which was part of the $9.5 billion bailout package SoftBank signed with WeWork following WeWork’s failed IPO.
Le Sirenuse Restaurant & Champagne Bar at The Surf Club The Latest Permanent Closure Due To COVID-19
COVID-19’s impact on the restaurant industry and commercial real estate is beginning to show its ugly face. Just several years after their well received March 2017 opening, Le Sirenuse Restaurant & Champagne Bar at The Surf Club has permanently closed its doors citing the fallout from the COVID-19 pandemic.
COVID-19’s impact on the restaurant industry and commercial real estate is beginning to show its ugly face. Just several years after their well received March 2017 opening, Le Sirenuse Restaurant & Champagne Bar at The Surf Club has permanently closed its doors citing the fallout from the COVID-19 pandemic. The Surfside location was the first Le Sirenuse location outside of Positano, Italy, where the original restaurant is located at Hotel Le Sirenuse. Le Sirenuse Restaurant & Champagne Bar at the Surf Club was located in The Four Seasons Hotel & Residences at The Surf Club, at 9011 Collins Ave. The ultra-luxury hotel-condo development was developed by Fort Partners, led by Nadim Ashi and delivered in 2017. The Surf Club Restaurant by Thomas Keller, which is also located at The Four Seasons Hotel & Residences at The Surf Club, remains open.
The Surf Club has been an integral part of the cultural history of Miami Beach since its inception as a private social club in the 1930's. The Four Seasons branded redevelopment led by Fort Partners broke ground in March 2014. The building features a 77 room hotel and 150 residences across three glass towers, two of which are residential and one hotel.
Swire Properties Sells Two Brickell City Centre Office Buildings For $163 Million Amid Pandemic
Swire Properties has sold Two Brickell City Centre and Three Brickell City Centre for a combined $163 million, $630 per square foot, amid the COVID-19 pandemic. Each Class A Office building is roughly 130,000 square feet with the pricing broken down by $80.3 million for Two Brickell City Centre and Three Brickell City Centre sold for $82.7 million.
Swire Properties has sold Two Brickell City Centre and Three Brickell City Centre for a combined $163 million, $630 per square foot, amid the COVID-19 pandemic. Each Class A Office building is roughly 130,000 square feet with the pricing broken down by $80.3 million for Two Brickell City Centre and Three Brickell City Centre sold for $82.7 million. The buyer was reportedly the Santa Monica-based Northwood Investors. Tenants of the office buildings include the law firm Akerman LLP, McKinsey & Company, and WeWork. The properties were first marketed for sale in January 2020.
Swire Properties plans to use the proceeds to fund future development, they have Brickell City Centre’s Phase 2 planned in partnership with Carlos Mattos to build a 100,000 SF expansion with a 54-story, 588-unit residential tower, and a 62-story, 384-unit residential tower with commercial space and additional parking.
Two Brickell City Centre and Three Brickell City Centre are located at 78 Southwest Seventh Street and 98 Southeast Seventh Street. Brickell City Centre was completed in 2016 and designed by Arquitectonica. The development features an opener shopping mall anchored by Saks Fifth Avenue, Casa Tua Cucina and CMX Theaters, the Rise and Reach condo towers and the East Hotel.
Neiman Marcus To Close Worth Avenue Location After Filing Chapter 11 Bankruptcy
COVID-19 continues to shake the commercial real estate industry, especially when it comes to retail. The Dallas-based Neiman Marcus Group has announced that they will be will be closing their Worth Avenue location in Palm Beach amid the luxury retailer’s Chapter 11 Bankruptcy Protection Proceedings.
COVID-19 continues to shake the commercial real estate industry, especially when it comes to retail. The Dallas-based Neiman Marcus Group has announced that they will be will be closing their Worth Avenue location in Palm Beach amid the luxury retailer’s Chapter 11 Bankruptcy Protection Proceedings. Neiman Marcus is actively working with A&G Real Estate to find someone to take over their 48,661 SF lease at 151 Worth Avenue which runs through May 31, 2026 and has options available to the tenant through 2051. 151 Worth Avenue is owned by the New York-based O’Connor Real Estate Advisors who acquired the property in January 2014 for $40 million.
"Real estate is a long-term play. These leases represent an incredible opportunity for retailers and investors to gain a foothold in markets that, under normal conditions, are renowned for their traffic and sales – as well as for their high barriers to entry," said A&G Real Estate Co-President Emilio Amendola. "Additionally, some of these locations are particularly promising for conversion to hotel, office or residential use."
The Worth Avenue, Palm Beach store currently remains open for curbside pickup and appointments only. Neiman Marcus first filed for Chapter 11 Bankruptcy in May 7, 2020, amid the fallout from the COVID-19 pandemic in the U.S. Bankruptcy Court for the Southern District of Texas, Houston Division.
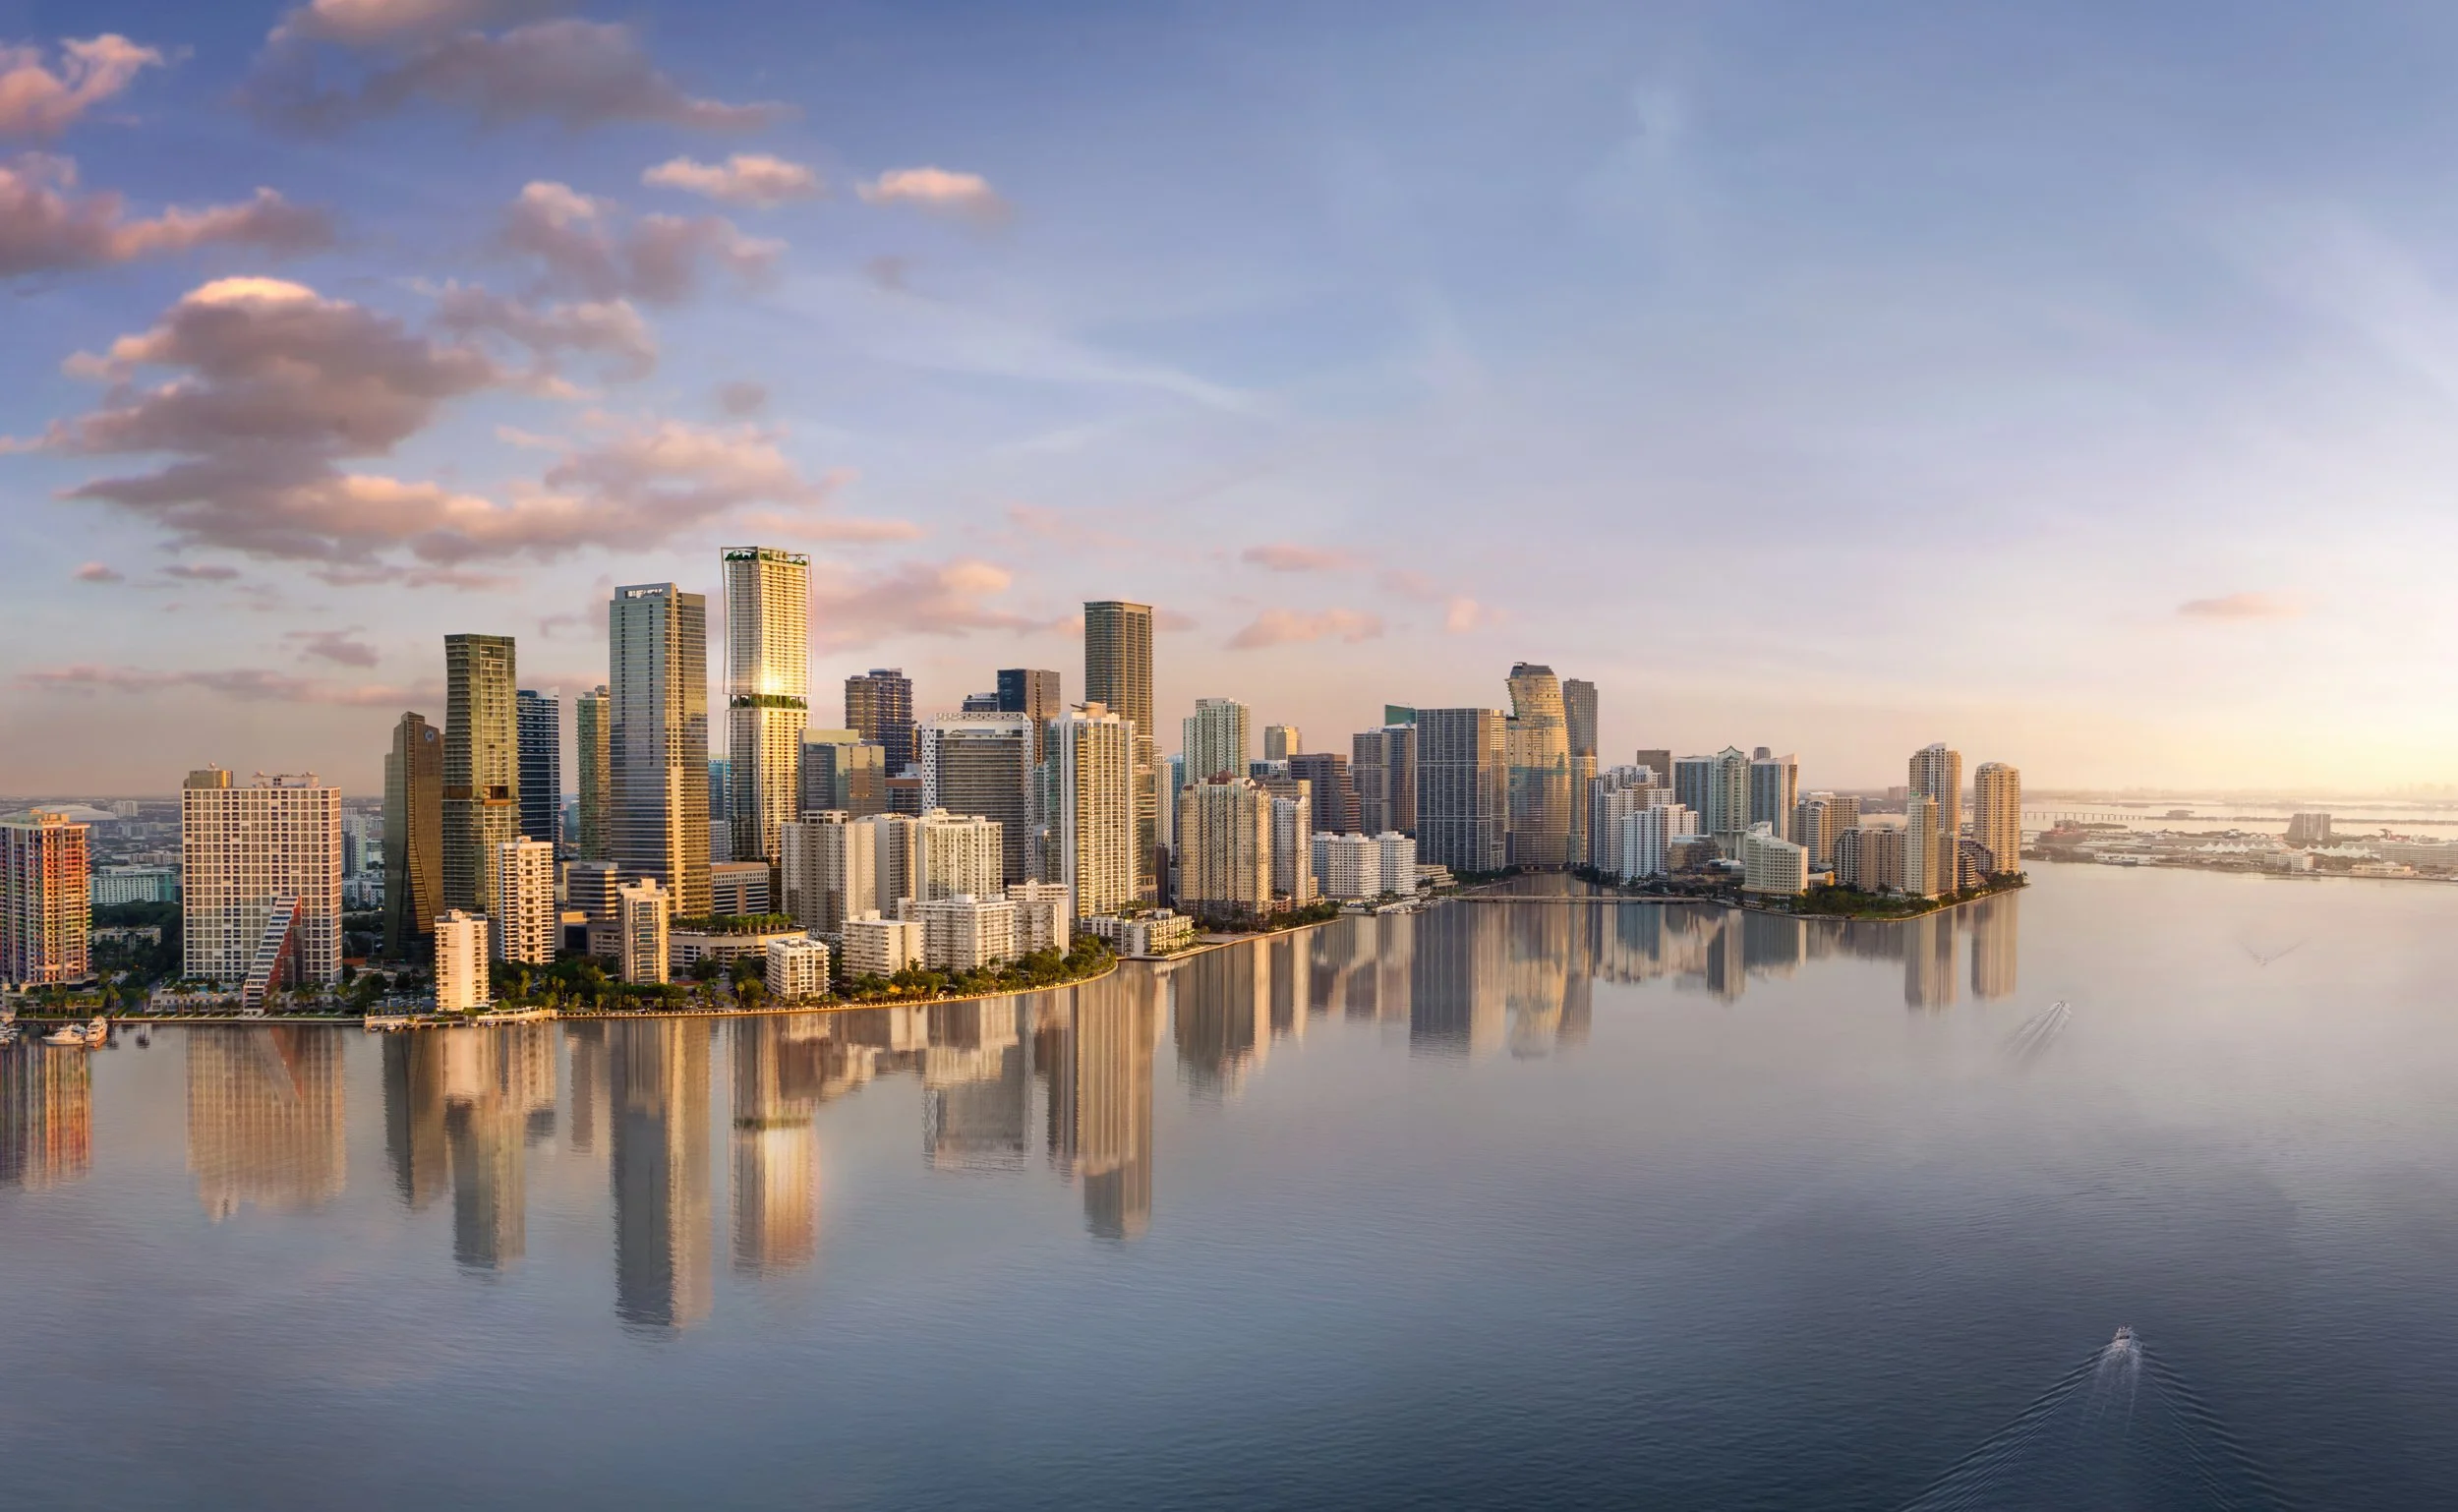
Pagani Residences has installed 33 custom 3D-printed Living Seawall panels by Kind Designs along its Biscayne Bay waterfront in North Bay Village.